Key Summary
OneMain Financial occupies a somewhat unusual spot in the personal lending landscape. Unlike most of the online-first lenders that dominate this space, OneMain has built its business around physical branches spread across the country, offering both unsecured and secured personal loans to borrowers who often have below-average or limited credit history. That branch network, combined with a willingness to lend to borrowers other companies decline, has made it a familiar name for people who want to sit down with someone in person rather than navigate an entirely digital application.
If you are researching OneMain and want to know what else is out there, this guide covers the strongest alternatives, what actually separates each one, and how to figure out which fits your specific credit situation, loan size, and preference for in-person versus fully online lending.
What Sets OneMain Apart From Most Online Lenders
The most distinctive thing about OneMain is its physical footprint. Where most competitors in this space operate exclusively online, OneMain maintains branch locations that let borrowers apply, sign documents, and in some cases receive funds in person. This matters for a specific group of borrowers: people who are less comfortable with a fully digital process, who want to ask questions face to face, or who need same-day funding through a local branch rather than waiting on an online transfer.
The second distinguishing feature is that OneMain offers both unsecured and secured loans. A secured loan, backed by collateral such as a vehicle, generally comes with a lower rate than an unsecured loan from the same lender, since the collateral reduces the lender’s risk. This dual structure gives OneMain more flexibility to work with borrowers who might not qualify for an unsecured loan on its own.
The tradeoff for this accessibility is cost. OneMain’s rates, particularly on unsecured loans, tend to run on the higher end compared to lenders that only serve borrowers with stronger credit, and origination fees are common.
Why Someone Might Look Beyond OneMain
Even among borrowers who value the in-person option, OneMain is not automatically the cheapest or best-structured loan available. Some alternatives offer better rates for a similar credit profile, some offer larger loan amounts, and some skip the origination fee entirely. If a physical branch is not essential to you, or if your credit is a bit stronger than OneMain’s typical borrower, comparing a few alternatives before committing is worth the time.
Alternatives to OneMain Financial
1. Avant
Avant serves a similar fair-to-average credit segment as OneMain but operates entirely online, with a faster, more streamlined application than a branch visit requires. Its administration fee is comparable in concept to OneMain’s origination fee, and its rates land in a similar range for borrowers without strong credit.
2. LendingPoint
LendingPoint uses underwriting that looks beyond credit score alone, factoring in income and other financial data. For a borrower who has been declined at a more traditional lender due to a thin credit file rather than a genuinely poor payment history, LendingPoint’s broader evaluation approach can be worth comparing against OneMain’s more traditional underwriting.
3. OppLoans
OppLoans specifically targets borrowers with less than perfect credit, positioning itself as an alternative to payday lending with a longer repayment structure. It tends to serve a similar or slightly lower credit tier than OneMain, making it a relevant comparison for borrowers who may not qualify for OneMain’s unsecured product.
4. Oportun
Oportun focuses on borrowers with thin or limited credit history, including people newer to using credit in the US. Like OneMain, it has maintained some physical locations in certain markets alongside its digital application, which is a rarer combination among OneMain’s online-first competitors.
5. Credit Unions Offering Secured or Signature Loans
Local and regional credit unions frequently offer both secured loans, similar in structure to OneMain’s collateral-backed product, and unsecured signature loans, often at meaningfully lower rates than OneMain for members with an existing relationship at the institution. Credit unions also tend to offer in-person service, which mirrors part of OneMain’s appeal.
6. Upstart
Upstart’s AI-driven underwriting, which factors in education and employment history alongside credit data, can be a stronger fit than OneMain for a borrower with a limited credit history but strong income potential, such as a recent graduate, since this profile often does not benefit much from OneMain’s more traditional risk assessment.
7. Beem
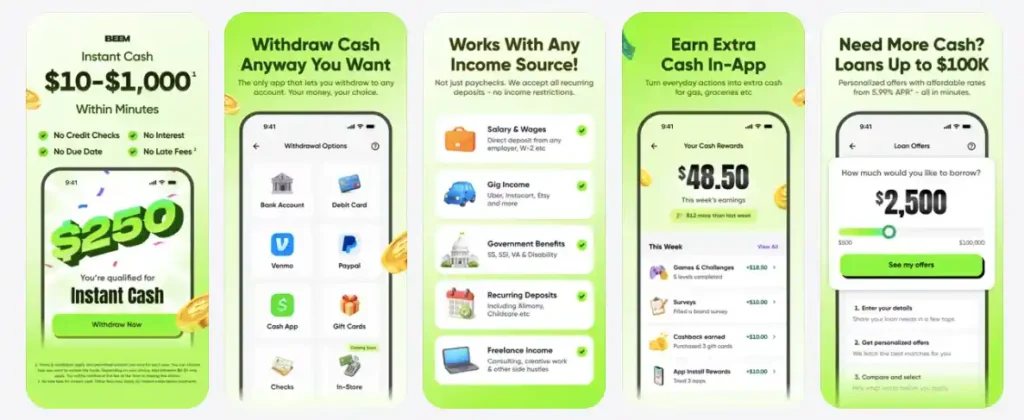
For borrowers who need a smaller amount rather than a larger secured or unsecured installment loan, Beem offers personal loan and cash advance options with transparent terms and no hidden fees. Beem does not restrict eligibility based on traditional W-2 income, supporting gig work, freelance earnings, and government benefits including SSI, SSDI, unemployment, and VA benefits, which can make it a faster, more accessible option for a smaller, more immediate need than a full OneMain application would require.
Secured Versus Unsecured: A Factor Unique to This Comparison
What OneMain’s Secured Loans Actually Involve
A secured loan through OneMain typically uses a vehicle as collateral, which can lower your interest rate compared to an unsecured offer from the same application. The tradeoff is real: if you fail to repay, the lender has a legal claim to seize the collateral, which is a meaningfully different risk than defaulting on an unsecured loan.
Why Few Alternatives Offer This Same Structure
Most of the online-first lenders in this comparison, including Avant, LendingPoint, OppLoans, and Upstart, only offer unsecured loans. This means if a lower rate through collateral is specifically what you are after, your realistic alternatives to OneMain narrow mainly to credit unions, many of which also offer secured personal loan products.
Weighing Whether Secured Is Worth It for You
A secured loan makes the most sense if the rate reduction is substantial and you are confident in your ability to make every payment, since the asset backing the loan is genuinely at risk. If you are not fully confident in your repayment ability, the lower rate may not be worth the added risk compared to a slightly higher-rate unsecured loan elsewhere.
The In-Person Factor: Does It Actually Matter to You?
When Branch Access Genuinely Helps
Some borrowers prefer discussing loan terms with a person directly, asking questions in real time, or handling paperwork somewhere other than a phone screen. If English is not your first language, or if you simply find financial paperwork easier to navigate with someone walking you through it, this is a legitimate reason to prioritize OneMain or Oportun, the two options here with meaningful in-person access, over a purely digital alternative.
When It Is Just a Preference, Not a Need
If your comfort with online applications is not really in question, and the branch visit is more about habit than necessity, expanding your comparison to fully digital lenders like Avant, LendingPoint, or Upstart opens up more competition on rate and fee structure, since these companies are not carrying the overhead cost of maintaining physical locations.
How to Calculate Whether Any of These Actually Beats OneMain
Start With Your Actual OneMain Offer
Rather than comparing based on advertised rate ranges, get your actual prequalified or approved terms from OneMain first, including whether you are being offered a secured or unsecured product and what the origination fee looks like.
Get at Least One Comparable Offer Elsewhere
Use prequalification tools with a soft credit check, which most of these alternatives offer, to see a real, personalized rate from at least one comparable lender, ideally one serving a similar credit tier to what OneMain approved you for.
Compare Total Repayment Cost, Not Just the Rate
Add the origination or administration fee into your comparison and calculate the full amount you would repay over the loan term with each option, rather than judging based on the interest rate alone.
Factor In What You Actually Value Beyond Cost
If in-person service or a secured loan option is genuinely important to you, weigh that against a purely cost-based comparison, since the cheapest loan on paper is not automatically the right choice if it does not fit how you actually want to manage the process.
Common Mistakes When Comparing OneMain to Other Lenders
Assuming All Alternatives Offer a Secured Option
Most of the fully online lenders on this list, unlike OneMain, only offer unsecured products. If a lower secured rate is central to your decision, narrowing your comparison to credit unions and OneMain itself, rather than the online-only competitors, will save you time.
Overlooking the Origination or Administration Fee
Nearly every lender in this comparison, OneMain included, charges some form of upfront fee deducted from your loan amount. Comparing rates without factoring this in can lead to an inaccurate sense of which option is actually cheaper.
Not Confirming State Availability
Several of these lenders, OneMain included, do not operate in every state, and physical branch access specifically is limited to states where OneMain has a location. Confirm availability in your area before spending time comparing further.
When OneMain Financial Itself Might Still Be the Right Choice
If you specifically value in-person service, need a secured loan option to access a lower rate than your credit alone would qualify for, and your state has a nearby branch, OneMain’s core value proposition genuinely holds up against most of its alternatives, few of which combine all three of these features.
When an Alternative Is Likely the Better Fit
If you are comfortable with a fully digital process, your credit sits a bit above OneMain’s typical borrower, or you specifically need a smaller loan amount without the overhead of a larger installment structure, Avant, LendingPoint, Upstart, or Beem are each likely to offer either a better rate, a faster process, or a more appropriately sized product for your specific need.
Final Thoughts
OneMain Financial’s combination of branch access and both secured and unsecured lending options makes it a genuinely distinct choice in a market otherwise dominated by fully digital lenders. But that distinctiveness does not automatically make it the cheapest or best-fitting option for every borrower. Avant, LendingPoint, OppLoans, Oportun, credit unions, Upstart, and Beem each serve a similar or adjacent segment with their own tradeoffs in rate, fee structure, and process. Getting your actual OneMain offer first, then comparing it against at least one alternative’s real prequalified terms, is the most reliable way to know whether OneMain’s branch access and collateral option are worth what they cost compared to a fully online alternative.
FAQs: Banks Like OneMain
What makes OneMain Financial different from most other personal loan lenders?
OneMain operates physical branch locations across the country and offers both secured loans backed by collateral and unsecured loans, a combination that most fully online lenders in this space do not offer.
Which OneMain alternatives also offer secured loan options?
Among the alternatives covered here, credit unions are the most likely to offer a comparable secured loan product, since most fully online lenders like Avant, LendingPoint, and Upstart only offer unsecured personal loans.
Is OneMain Financial more expensive than online-only lenders?
It can be, particularly for unsecured loans, since OneMain serves a fair-to-poor credit segment and charges an origination fee, though a secured loan through OneMain may offer a lower rate than an unsecured loan from a purely online competitor for the same borrower.
Does OneMain Financial require a branch visit to apply?
No, OneMain offers both online and in-person application options, though its branch network is a key differentiator for borrowers who specifically want in-person support during the process.
Is Beem a good alternative to OneMain for a smaller loan need?
Yes, if you need a smaller amount without the overhead of a larger secured or unsecured installment loan, Beem’s personal loan and cash advance options offer a faster, more accessible path with transparent terms and no hidden fees.