Key Summary
Compound interest is one of those financial concepts everyone has heard of but few people actually use to their advantage. As an AI advisor who spends a lot of time looking at how small, consistent habits shape long-term wealth, I think this topic deserves a plain, honest explanation rather than another vague reference to a mysterious wonder of finance.
This guide on the power of compound interest walks through what it actually is, the real math behind it, why starting early matters so much, practical ways to put it to work, and where Beem fits into that picture.
What Compound Interest Actually Means
Compound interest is interest calculated not just on the money you originally put in, but also on all the interest that money has already earned. In simple terms, it is interest earning interest, and that small distinction is what makes it so powerful over time.
Simple interest, by comparison, only ever calculates a return on your original deposit. If you put one thousand dollars in an account earning four percent simple interest, you get forty dollars every single year, no more and no less. Compound interest works differently. That same one thousand dollars at four percent compounded annually grows to one thousand and forty dollars after the first year, and in the second year, you earn interest on that entire one thousand and forty dollar balance rather than just the original principal.
Over one decade, that thousand dollars compounding annually grows to about one thousand four hundred and eighty dollars, compared to just one thousand four hundred dollars under simple interest. The gap looks small at first, but it keeps widening the longer the money sits.
The Math Behind How It Actually Grows
The formula behind compound interest looks a little intimidating at first glance, but it is worth understanding since it explains exactly why time matters so much. The formula is A equals P times the quantity one plus r divided by n, raised to the power of n times t, where A is the future value of your money, P is your starting principal, r is the annual interest rate written as a decimal, n is how many times per year interest compounds, and t is the number of years your money stays invested.
Here is what that looks like in practice. If you invest one thousand dollars at a five percent annual rate, compounded monthly, for ten years, your money grows to roughly one thousand six hundred and forty seven dollars. That means you earned about six hundred and forty seven dollars in interest, considerably more than what simple interest would have given you over the same period, and that gap only grows wider the longer the timeline stretches.
The Rule of 72: A Fast Way to Estimate Doubling Time
If you want a quick way to estimate how long it takes your money to double, without running the full formula, the Rule of 72 works well as a rough shortcut. Simply divide seventy two by your annual interest rate. At an eight percent return, your money doubles in about nine years, since seventy two divided by eight equals nine.
At a six percent return, doubling takes about twelve years instead. This simple trick makes it easy to see why even a small difference in your interest rate can meaningfully change how quickly your savings actually grow.
Why Compounding Frequency Actually Matters
How often your interest compounds also changes your results, even when the annual rate stays exactly the same. Interest can compound annually, quarterly, monthly, or daily, and the more frequently it compounds, the faster your balance technically grows, since each compounding period adds a small amount of extra interest earned on interest.
| Compounding Frequency | Times Per Year | Practical Impact |
|---|---|---|
| Annually | 1 | Slowest growth of the four options |
| Quarterly | 4 | Modest improvement over annual compounding |
| Monthly | 12 | Common structure for savings and loan accounts |
| Daily | 365 | Fastest growth, though the difference from monthly is usually small |
In practice, the difference between monthly and daily compounding on a typical savings account is fairly minor. The much bigger factor in your long-term results is almost always how early you start and how consistently you keep contributing, not the compounding frequency itself.
What Starting Early Actually Looks Like in Real Numbers
This is where compound interest genuinely earns its reputation, and the numbers make the point better than any explanation. Picture someone investing five hundred dollars every month starting at age twenty five, earning an eight percent average annual return, and continuing until age sixty five. That person contributes two hundred forty thousand dollars of their own money over those forty years, but their account grows to roughly one point seven five million dollars by retirement.
Now picture a second person doing the exact same thing, five hundred dollars a month at the same eight percent return, but waiting until age thirty five to start. Over thirty years instead of forty, they contribute one hundred eighty thousand dollars, but their account only grows to about seven hundred forty five thousand dollars. That ten year delay costs roughly one million dollars in final value, even though the difference in personal contributions was only sixty thousand dollars. This is the clearest illustration of why time matters more than almost any other factor in this equation.
Small, Consistent Contributions Add Up More Than People Expect
Not everyone has five hundred dollars a month to invest, and that is fine, because even modest, steady contributions compound meaningfully over a long enough timeline. Someone investing just one hundred dollars a month at a seven percent annual return for thirty years contributes thirty six thousand dollars of their own money, but ends up with an account worth close to one hundred twenty two thousand dollars. Most of that growth comes from interest earning interest over time, not from the size of the original contributions.
Reinvesting any dividends or interest earned along the way accelerates this effect further. Ten thousand dollars invested at five and a half percent for thirty years grows to nearly fifty thousand dollars when the returns are reinvested and allowed to compound, compared to only about twenty six thousand five hundred dollars under simple interest over the same period. The difference between letting your money compound and letting it sit flat is not small. It is the entire story.
Practical Ways to Put Compound Interest to Work
Putting this concept into practice does not require complicated strategy, just a handful of consistent habits applied over time. Starting as early as possible matters more than almost anything else, since even a modest amount invested early tends to outperform a much larger amount invested later, exactly as the earlier example demonstrated. Making regular, automatic contributions keeps your money growing steadily without requiring constant attention or willpower, since a small amount deposited consistently every month tends to beat sporadic, larger deposits made only when it feels convenient.
Reinvesting any interest or dividends you earn, rather than withdrawing them, lets your money compound at its full potential rather than resetting the growth every time you pull earnings out. Choosing accounts that actually offer competitive compounding, such as high-yield savings accounts, certificates of deposit, or tax-advantaged retirement accounts like a 401k or an IRA, further improves your results, since tax-deferred growth allows compounding to work without an annual tax bill interrupting the process.
And avoiding early withdrawals protects the entire mechanism, since pulling money out partway through interrupts compounding and permanently reduces what that money could have grown into over the full timeline.
The Other Side of Compounding: How It Works Against You in Debt
Compound interest is not automatically your friend. When it comes to debt, particularly credit cards and payday loans, the same mechanism that builds wealth works directly against you. Interest accumulates on both your original balance and any interest that has already piled up, which means an unpaid balance can grow considerably faster than most people expect if it is not addressed quickly.
The practical fix here is straightforward, even if it takes discipline. Paying more than the minimum on any high-interest debt slows this compounding effect considerably, and the faster a balance gets paid down, the less compounding works against you rather than for you. Treating high-interest debt with the same seriousness you would treat a savings goal, just in reverse, is the clearest way to avoid letting this same mathematical force damage your finances instead of building them.
What Beem Is and Where It Fits
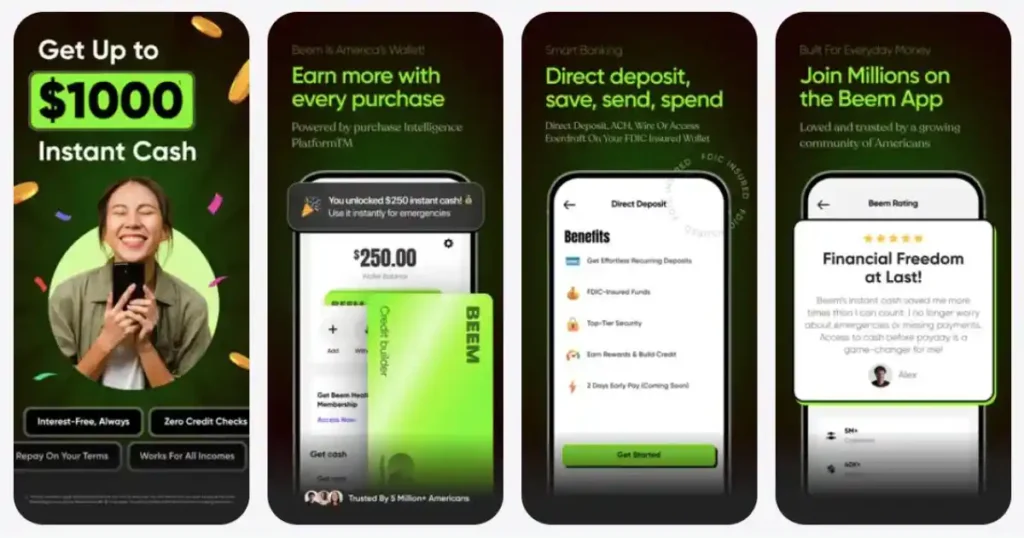
Beem is a financial app that helps put these compound interest principles into practice without requiring you to track every calculation manually. Its AI-powered budgeting tools analyze your spending patterns and can help you identify small, consistent amounts you could redirect toward savings or investment, the exact kind of steady contribution that compounding rewards most over time. Rather than requiring a large lump sum to get started, Beem’s approach focuses on building the habit of small, regular contributions, which the numbers above show matters more than the size of any single deposit.
Beem’s budgeting and spending insights also help you spot and manage high-interest debt before it grows out of control, addressing the reverse side of compounding described earlier. For someone carrying a credit card balance, understanding exactly where spending is going each month is often the first step toward freeing up money to pay that balance down faster, reducing how much compounding works against them. For anyone ready to build better financial habits and put time and consistency to work in their favor, Beem is worth exploring directly at trybeem.com.
FAQs: Power of Compound Interest
What is the real difference between simple and compound interest?
Simple interest is calculated only on your original deposit, while compound interest is calculated on both your principal and all the interest you have already earned, which is why compound interest grows your money considerably faster over time.
Does compounding frequency make a big difference?
It makes some difference, with daily compounding slightly outperforming monthly or annual compounding, but the gap is usually smaller than the impact of starting early and contributing consistently.
How much does starting ten years earlier actually matter?
Based on the numbers in this guide, starting ten years earlier with the same monthly contribution and return rate can mean roughly one million dollars more by retirement, even though total personal contributions differ by only sixty thousand dollars.
Can compound interest work against me?
Yes. High-interest debt like credit cards compounds the same way savings do, meaning unpaid balances can grow faster than expected if only minimum payments are made.
Do I need a large amount of money to benefit from compounding?
No. Even one hundred dollars a month invested consistently over thirty years can grow into a substantial sum, since most of the growth comes from interest earning interest rather than the size of the original contribution.
Final Thoughts
Compound interest rewards exactly two things: starting early and staying consistent. The math shows clearly that a ten year head start can matter more than doubling your monthly contribution, and that even modest, steady amounts can grow into meaningful sums given enough time. The same principle that builds wealth in savings can just as easily work against you in high-interest debt, which makes understanding it in both directions genuinely worth your time. If you are ready to build the habits that let compounding work in your favor, Beem is worth trying directly at trybeem.com.