Key Summary
Medical expenses are among the most financially disruptive costs a household can face. They arrive without warning, often at the worst possible time, and carry price tags that most people cannot cover out of pocket in a single payment. That is exactly why BNPL in healthcare is gaining rapid traction across the United States. Buy now pay later options for medical bills give patients a way to access the care they need immediately while spreading the cost over time in structured, manageable payments.
This guide explains how BNPL in healthcare works, who it serves best, what to watch out for, and how platforms like Beem offer fast, flexible financial support to help you manage healthcare costs without derailing your broader financial situation.
What Is BNPL in Healthcare?
BNPL in healthcare is the application of buy now pay later financing to medical expenses. Originally popularized in retail, the BNPL model splits a total cost into a series of smaller installment payments made over a fixed period, often with low or zero interest for qualified users. Applied to healthcare, this means patients can receive treatment, prescriptions, dental work, vision care, mental health services, or elective procedures today and pay for them gradually rather than all at once.
The model is designed to remove the financial barrier that causes patients to delay or avoid necessary care. When a $600 dental procedure or a $400 specialist visit requires full payment upfront, many patients choose to postpone treatment rather than disrupt their monthly budget. BNPL in healthcare removes that constraint by making the total cost smaller in the moment, even though the overall amount remains the same.
How Buy Now Pay Later Works for Medical Bills
The mechanics of BNPL for medical expenses are similar to retail BNPL but adapted for the healthcare billing environment. A patient receives treatment or is presented with a bill and is offered a financing option at the point of service. They apply for a payment plan through a BNPL provider, receive an instant eligibility decision, and begin making installment payments on a weekly or monthly schedule.
Some BNPL healthcare products operate at the provider level, meaning the hospital or clinic directly partners with a financing company. Others operate through third-party apps or financial platforms that the patient initiates independently. Both approaches result in the same outcome: the upfront cost of care is reduced to a manageable installment, and the patient receives treatment without delay.
Why BNPL in Healthcare Is Growing Fast
Healthcare costs in the United States have risen consistently for decades, and insurance coverage has not kept pace with that growth. Deductibles, copays, coinsurance, and out-of-pocket maximums have increased significantly, leaving patients responsible for a larger share of their medical bills than at any point in recent history.
According to research from the Kaiser Family Foundation, a significant portion of American adults report having difficulty paying a medical bill, and many have delayed care specifically because of cost concerns. These are not uninsured individuals. Many are fully insured patients whose coverage still leaves them with hundreds or thousands of dollars in out-of-pocket expenses per episode of care.
BNPL in healthcare addresses this structural gap by providing a payment layer that exists between the cost of care and what insurance actually covers. It does not reduce the bill, but it transforms the impact of the bill by spreading it over time in a way that is compatible with a normal monthly budget.
Who Benefits Most From Healthcare BNPL
The patients who benefit most from BNPL in healthcare fall into several clear groups. People with high-deductible health plans face significant out-of-pocket costs before insurance kicks in and are among the most common users of healthcare financing tools. Self-employed individuals and gig workers who purchase their own insurance often carry higher deductibles as a cost-control measure and face the same challenge.
Uninsured and underinsured adults who access care out of pocket represent another major group. For these users, BNPL is often the difference between receiving necessary treatment and going without. Patients seeking elective but medically appropriate procedures such as dental work, vision correction, physical therapy, or mental health services are also strong candidates for BNPL financing, since many insurance plans limit or exclude coverage for these categories entirely.
Read: Beem to Cash App for Medical Bills: A Faster Alternative to Loans
Best Buy Now Pay Later Options for Medical Bills
Several platforms have entered the healthcare BNPL space, each with a different approach to eligibility, coverage, repayment terms, and the types of care they support. Understanding the options helps patients choose the model that fits their specific financial situation and treatment needs.
CareCredit: Best Established Healthcare Credit Option
CareCredit is one of the longest-running healthcare financing products in the market and is accepted at more than 250,000 provider locations across the United States. It functions as a dedicated healthcare credit card that can be used for medical, dental, vision, veterinary, and cosmetic services.
How CareCredit Works
CareCredit offers promotional financing periods ranging from six to 24 months with deferred interest, meaning no interest is charged if the full balance is paid within the promotional window. If the balance is not cleared by the end of the promotional period, interest is applied retroactively from the original purchase date, which can result in a significant additional cost.
The card requires a credit application and approval based on creditworthiness, which means users with limited or poor credit history may not qualify for the most favorable terms. For patients with solid credit who can commit to paying off the balance within the interest-free period, CareCredit offers real value. For those who cannot reliably clear the balance in time, the retroactive interest structure can make it an expensive option.
Affirm: Best BNPL Option for Transparent Installment Plans
Affirm is a widely used BNPL platform that has expanded into healthcare financing through partnerships with select providers and health-focused platforms. It offers installment loans with fixed payment schedules and clear upfront terms, which removes the retroactive interest risk present in some deferred-interest products.
How Affirm Works for Medical Expenses
Affirm shows the total cost of financing, including any interest, before the user accepts the loan. Repayment terms typically range from three to 36 months depending on the loan amount and the user’s eligibility. Interest rates vary based on creditworthiness, and some promotional zero-interest offers are available through specific partner providers.
The transparency of Affirm’s model is its primary strength. Users know exactly what they will pay from the start with no surprise charges at the end of a promotional window. The limitation is that availability depends on whether the healthcare provider or billing platform has a direct Affirm integration, which is not universal across all medical settings.
Splitit: Best Option for Patients With Existing Credit
Splitit works differently from most BNPL providers. Rather than issuing a new credit line, it allows users to divide a total charge across multiple installments using an existing Visa or Mastercard credit card. No new credit application is required, and no credit check is performed at the time of using Splitit.
How Splitit Works
The total medical bill amount is held as a temporary authorization on an existing credit card. Each month, only the installment amount is charged while the remaining hold is adjusted accordingly. For patients who already have available credit and want to spread payments without opening a new account or undergoing a fresh credit review, Splitit provides a frictionless solution.
The limitation is that Splitit requires sufficient available credit on an existing card. For patients who are already near their credit limit or who do not have an eligible card, this option is not accessible.
Sunbit: Best BNPL for In-Office Healthcare Financing
Sunbit has built a healthcare-specific BNPL product with a focus on high approval rates, including for patients with limited credit history. It is offered directly at provider locations, primarily dental and optical offices, and processes decisions in under a minute at the point of service.
How Sunbit Works
Sunbit claims to approve the majority of applicants regardless of credit score, which makes it one of the more inclusive options in the healthcare BNPL category. Repayment terms range from three to 72 months, and the product is designed to be used at the time of service rather than applied for independently in advance.
The in-office model means Sunbit is only available where providers have a direct partnership. Patients cannot independently initiate a Sunbit plan for a bill received after the fact.
Beem: Best Flexible Option for Instant Healthcare Cash Coverage
Beem stands out among healthcare financing options because it provides immediate, flexible cash access that can be applied to any medical expense, at any provider, without requiring a direct partnership between the platform and your healthcare provider. This removes one of the biggest limitations of integrated BNPL products, which is that they only work where the provider has already agreed to participate.
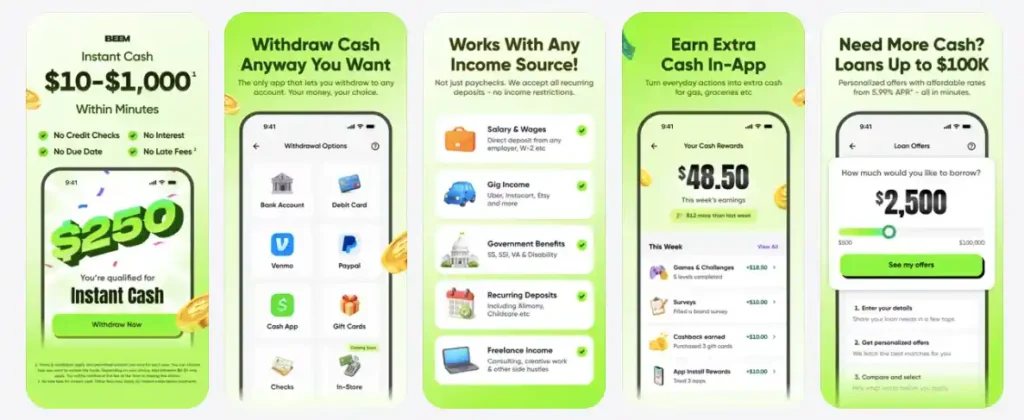
Through Beem’s instant cash advance feature, eligible users can access $10 to $1,000 in seconds with no interest, no credit check, and no rigid repayment deadline. For covering a copay, a prescription cost, a dental bill, an urgent care visit, or any other out-of-pocket medical expense, Beem delivers funds directly to a Beem Wallet, a debit card, a prepaid card, or as gift cards from major retailers, giving patients immediate purchasing power regardless of which provider or pharmacy they are using.
Why Beem Works for Healthcare Costs Other BNPL Products Miss
Most integrated BNPL healthcare products require your provider to be a participating partner. That means if your doctor, urgent care clinic, therapist, or pharmacy does not have a deal with CareCredit, Affirm, or Sunbit, you cannot use those products for that bill. Beem has no such limitation. Because Beem delivers cash or card-based funds directly to you rather than paying a provider directly, you can use it for any healthcare expense, including those at providers who do not offer any financing at the point of service.
This universality is particularly important for mental health appointments, telehealth visits, out-of-network specialist care, pharmacy costs, and emergency medical situations where there is no time to explore financing options at checkout. Beem handles these situations in seconds with no credit check and no interest.
For larger medical expenses that exceed the cash advance range, Beem also provides access to personal loan comparisons ranging from $500 to $100,000. This gives users a path to larger healthcare financing options through a single platform, covering both small immediate costs and larger structured borrowing needs in one place.
Visit trybeem.com/personal-loan to explore personal loan options for larger medical expenses, or visit trybeem.com/get-instant-cash-advance to access an instant cash advance for healthcare costs right now.
BNPL in Healthcare vs Personal Loans for Medical Bills
Choosing between a BNPL product and a personal loan for healthcare costs depends on the size of the expense and the repayment timeline that works best for your financial situation.
BNPL in healthcare is best suited to smaller to mid-range medical bills that can realistically be repaid within a few months. The shorter timelines and smaller amounts keep total financing costs low, especially for zero-interest promotional products. For bills under $1,000, a cash advance through Beem covers the expense immediately with no interest at all, which is the most cost-efficient path available.
Personal loans are better suited to larger medical expenses such as surgery costs, extended hospital stays, fertility treatments, orthodontic care, or any healthcare bill that exceeds what a short-term advance or standard BNPL product can cover. Beem’s personal loan comparison tool surfaces offers from $500 to $100,000 without a hard credit inquiry, allowing users to explore options that match their specific healthcare financing need before committing to any single lender.
When to Use Each Option
Use a Beem cash advance when the medical expense is under $1,000, when you need funds immediately at any provider, or when you want zero-interest short-term coverage with no credit check. Use a personal loan comparison through Beem when the total healthcare cost is larger, when you need a structured multi-month repayment plan, or when you want to consolidate multiple medical bills into a single monthly payment.
Hidden Costs and Risks of BNPL in Healthcare
While BNPL in healthcare offers genuine value, not all products in this category are equally transparent or fair. Deferred interest models, like those used by some healthcare credit cards, can result in significant retroactive charges if the balance is not fully cleared within the promotional window. This is one of the most common sources of unexpected cost for healthcare BNPL users.
Late payment fees apply to most BNPL products and can add meaningful cost to an already stressful financial situation. Some providers charge account opening fees or monthly maintenance fees that are not prominently disclosed during the application process.
How to Evaluate BNPL Healthcare Products Safely
Before accepting any BNPL offer for a medical bill, confirm whether interest is truly deferred or truly zero. Deferred interest is not the same as zero interest. Deferred interest means no interest is charged during the promotional period but all interest accrues retroactively if the balance is not paid in full by the deadline. True zero interest means no interest applies regardless of how long repayment takes.
Read the full repayment terms before signing. Understand what happens if you miss a payment, what fees apply, and whether the repayment schedule is compatible with your actual monthly income timing. Platforms that are fully transparent about every cost before you commit, like Beem, reduce this risk significantly by showing all terms upfront.
The Future of BNPL in Healthcare
The growth of BNPL in healthcare is accelerating as patient out-of-pocket costs continue to rise and consumer demand for flexible payment options increases. Healthcare providers are recognizing that offering financing at the point of service increases the likelihood that patients follow through with recommended treatment rather than delaying due to cost concerns.
Regulatory attention on BNPL products broadly is also increasing, with consumer protection agencies examining deferred interest structures, disclosure requirements, and the potential for BNPL to contribute to consumer debt burdens. This increased scrutiny is likely to push the market toward more transparent and standardized product terms, which benefits patients.
For consumers navigating healthcare costs today, the most important principle is choosing tools that deliver genuine value without hidden complexity. Beem’s combination of instant cash advances for immediate needs and personal loan comparisons for larger expenses makes it one of the most practical and transparent financial platforms for managing healthcare costs across a wide range of situations.
Check out Beem for on-point financial insights and recommendations to spend, save, plan and protect your money like an expert. Download the Beem app today!
Frequently Asked Questions
What is BNPL in healthcare?
BNPL in healthcare stands for buy now pay later applied to medical expenses. It allows patients to access care immediately and spread the total cost across installment payments over time rather than paying the full amount upfront. It is used for medical, dental, vision, mental health, and other healthcare services.
What are the best buy now pay later options for medical bills?
The best BNPL healthcare options include CareCredit for broad provider acceptance, Affirm for transparent installment terms, Splitit for patients with existing credit, Sunbit for high-approval in-office financing, and Beem for instant cash access that works at any provider with no credit check and no interest.
Can I use BNPL for any medical expense?
Integrated BNPL products like CareCredit and Sunbit require your provider to participate in their network. Beem is different because it delivers cash or card funds directly to you, meaning you can use it for any medical expense at any provider, including those without BNPL partnerships.
Does BNPL in healthcare affect my credit score?
This depends on the product. Some BNPL healthcare products perform a hard credit inquiry during the application process, which can temporarily affect your score. Beem’s instant cash advance requires no credit check of any kind, so your credit score is not impacted at any point during the process.
How does Beem help with healthcare costs?
Beem offers instant cash advances from $10 to $1,000 for eligible users with no interest, no credit check, and multiple payout options. For larger medical expenses, Beem’s personal loan comparison tool surfaces offers from $500 to $100,000 without a hard inquiry. Together, these tools cover both immediate and larger healthcare financing needs in one platform.