
Key Summary
Step markets itself as a teen-friendly banking app that helps young people build credit for free, which has led many to ask a simple question: Is Step legit? The short answer is yes. Step is a legitimate, FDIC-insured financial technology company with millions of users, a secured card that reports to all three credit bureaus, and no monthly fee on its basic plan.
The longer answer offers more nuance. Step is legit, but it was designed primarily for teens and young adults, not older adults building credit for the first time.
This guide explains how Step works, whether it is safe, how it builds credit, what it costs, and who it is best for. It also covers five simple tips for building credit as a beginner and where Beem fits as an option for adults who need higher limits and more comprehensive financial tools.
What Is Step and How It Works
Step is a banking app that launched in 2020 and is focused on teens and young adults. Its main product is a secured card that functions like a debit card while reporting activity to the credit bureaus. Everyday purchases can help users build credit history without borrowing money, paying interest, or accumulating debt.
Step partners with Evolve Bank & Trust and Stride Bank, both FDIC members, so deposits are insured up to $250,000. The secured card spends money already available in your Step account. Because you are not using a credit line or borrowing funds, you build credit by spending your own money and letting Step report that activity each month.
For users under 18, a parent or guardian must sponsor the account. The sponsor can view spending and set limits, helping families teach healthy money habits. Users 18 and older do not need a sponsor, though the app retains its teen-focused interface.
Step offers two account tiers. The basic account is free with no monthly fee. Step Black costs $4.99 per month, but the fee is waived with at least $500 in monthly direct deposits.
Step Black adds a higher savings rate, increased cashback, and access to EarlyPay—Step’s cash advance feature that lets qualifying users access up to $250 before payday. As with most cash advance services, users typically start with a lower limit and increase it over time.
Is Step Legit for Credit Building
Step is a legitimate company, not a scam. It serves more than 6.5 million users and is backed by well-known investors, with a multi-year track record without major regulatory issues. App store reviews are largely positive, particularly among teens and parents who appreciate its credit-building design.
Its credit-building feature is equally effective. Step reports that average users increase their credit scores by 57 points in their first year. While individual results vary depending on starting scores and card usage, Step reports to Equifax, Experian, and TransUnion. Regular, on-time activity establishes a positive payment history, which is the primary factor in credit scoring.
The credit-building claim holds up, too. Step says the average user raises their credit score by 57 points in the first year. Results always depend on your starting point and how often you use the card, but because Step reports to Equifax, Experian, and TransUnion, the credit-building engine is real. Regular, on-time activity builds a positive payment history, and payment history is the biggest factor in your credit score.
Step is both safe and legitimate, and the card fulfills its core promises. The key consideration is whether Step aligns with your age group and financial goals. For teenagers starting early, Step is an effective tool. For adults seeking higher cash advance limits or broader financial features, its scope may feel restrictive.
So when people ask whether Step is safe and legit, the honest answer to both is yes. The card does what it promises. The real question is not whether Step works. It is whether Step is the best fit for your age and your financial goals. For a teen starting early, Step is a strong tool. For an adult who wants higher cash advance limits or broader money features, Step can feel limited.
Read: Cash Advances and Credit Building Apps: Why Combining Both Makes Sense
How Step Builds Credit for Beginners
Step builds credit using a secured card that reports transactions to all three major credit bureaus. Every purchase—from groceries to gas—is reported, gradually establishing a payment history that forms the foundation of a credit score.
Because it functions as a secured card, you spend your own funds rather than borrowed capital. There is no interest or minimum payment requirement because you do not carry a balance or incur debt. Credit building occurs automatically through routine purchases.
This approach offers a safer entry point than a traditional credit card. Users cannot spend beyond their account balance, eliminating the risk of revolving debt or missed payments. This protective structure makes Step popular among younger users learning the fundamentals of credit.
Credit score growth corresponds directly with card usage frequency. Regular everyday use establishes a payment history faster than occasional transactions. Step’s 57-point average score increase reflects steady usage, with the most rapid gains usually achieved by individuals building a credit profile from scratch.
Step Costs and Fees
A key advantage of Step is that its basic account carries no cost. There are no monthly maintenance fees, overdraft fees, minimum balance requirements, or hidden charges—a notable feature in a market where subscription models are common.
Step Black costs $4.99 per month, but the fee is waived with $500 or more in monthly direct deposits. While adults with regular paychecks can easily meet this threshold to waive the fee, teenagers relying on allowances or part-time work may find it more challenging.
Step Black is the paid tier at $4.99 a month, but the fee disappears if you receive at least $500 in monthly direct deposits. For an adult with a steady paycheck, Step Black is effectively free. For a teen with an allowance or a part-time job, hitting that $500 threshold every month can be harder.
Here is a simple breakdown of what each tier includes:
| Feature | Step Basic | Step Black |
|---|---|---|
| Monthly fee | Free | $4.99 per month (waived with $500+ direct deposit) |
| Secured card with credit reporting | Yes | Yes |
| Savings rate | Standard | 4% high-yield |
| Cashback | Limited | 1%, up to 10% at select merchants |
| EarlyPay cash advance | No | Up to $250 |
| Fee-free ATMs (Allpoint) | Yes | Yes |
A few things to keep in mind on cost:
- EarlyPay advances are included with Step Black, though fees for instant transfers are not fully detailed in public materials. Most cash advance services charge for expedited transfers or request tips, so instant access may incur additional costs.
- Step provides access to more than 30,000 fee-free ATMs through the Allpoint network. While Step does not impose ATM fees, third-party out-of-network operators may still apply charges.
- The 4% savings yield and cashback rewards are exclusive to Step Black, leaving the free tier focused primarily on credit building rather than secondary perks.
Read: How Beem App Combines Instant Cash and Credit Building in One Place
Step Features and Pros
Step’s key features include a secured credit-building card with automatic reporting, EarlyPay cash advances, high-yield savings on Step Black, cashback rewards, and peer-to-peer transfers. Parental oversight tools allow guardians to manage allowances and set spending limits, encouraging financial literacy.
The primary advantage is accessible credit building at no cost on the basic tier. Without interest charges or monthly fees, users build credit simply by spending their available funds.
Additional notable advantages include:
- FDIC insurance through partner banks, securing deposits up to $250,000.
- A 4% savings yield on Step Black that competes favorably with traditional and online savings accounts.
- Parental control tools that make Step an effective choice for families introducing teenagers to credit management.
- A debt-free model that prevents common financial mistakes, such as overspending and accruing high-interest debt.
Step Cons and Limitations
Step’s main limitation stems from its design target: it is built primarily for teenagers. The branding, user interface, and marketing target a younger demographic. While adults can use the platform, the experience may feel tailored to younger users.
Here are the main drawbacks to weigh:
- Teen-centric orientation. The app’s layout and features are not tailored to adult financial responsibilities, such as rent, utilities, or larger recurring bills.
- Required sponsorship for minors. Users under 18 must have a parent or guardian sponsor, which limits financial autonomy for older teenagers.
- Fixed credit limit model. Because it functions as a secured card, you spend existing funds rather than receiving credit limit increases over time, meaning Step alone may not support long-term credit growth.
- Low cash advance cap. EarlyPay caps advances at $250, with lower initial limits for new users—a potential drawback when managing larger unexpected expenses.
- Tier-restricted perks. Premium features require either a $4.99 monthly subscription or a $500 monthly direct deposit, which not all young or part-time workers meet.
Read: 5 Things to Look for in a Credit-Building Banking App
5 Tips to Build Credit as a Beginner
Regardless of the platform you choose, sound credit-building principles remain constant. Below are five fundamental strategies for beginners starting without a credit history.
- Use a card that reports to all three credit bureaus. Credit history accumulates only when activity is reported to Equifax, Experian, and TransUnion. Secured cards like Step or the Beem Credit Builder Card report automatically, whereas non-reporting cards do not contribute to score calculation.
- Maintain consistent, on-time payments. Payment history is the most significant factor in credit scoring. Secured cards process payments at the point of sale, eliminating the risk of late payment. For traditional credit cards, enabling automatic payments helps prevent missed due dates.
- Maintain steady card usage. Using your card for routine transactions, such as fuel or groceries, establishes an active history. Active cards build credit profiles faster than unused accounts.
- Keep credit utilization low. When transitioning to traditional credit accounts, aim to utilize less than 30% of your total credit limit, with under 10% being ideal. Credit utilization is the second most influential factor in credit scoring.
- Monitor credit reports regularly. Review your credit reports annually for accuracy and dispute any discrepancies. Credit building requires consistent effort over time, with most beginners observing notable changes after 6 to 12 months of steady activity.
Who Should Use Step
Step is well-suited for teenagers ages 13 to 18 who are building credit under parental supervision. It also serves young adults aged 18 to 24 who do not require large cash advances or complex money-management tools.
Step is less suitable for older adults who require comprehensive credit-building options, higher advance limits, or advanced tools like automated budgeting and expense tracking. Its intentional simplicity benefits younger users but limits its utility for broader financial management.
Real User Experiences
User feedback is generally positive among teenagers and parents. Many users see their credit scores improve within a few months of regular card use, and parents value the opportunity to teach budgeting without exposing teens to debt risks.
The common complaints are worth knowing before you sign up:
Common user critiques include:
- EarlyPay advance limits start low and remain below expectations for some users.
- Some account holders report delayed customer support responses.
- Adult users occasionally find the youth-oriented branding ill-suited for their needs.
Overall feedback indicates that Step fulfills its primary goal of providing accessible credit building for younger users, though it lacks the feature depth desired by older audiences.
Read: Credit Scores for New Americans: Building History From Scratch With Beem
What Beem Is and Where It Fits
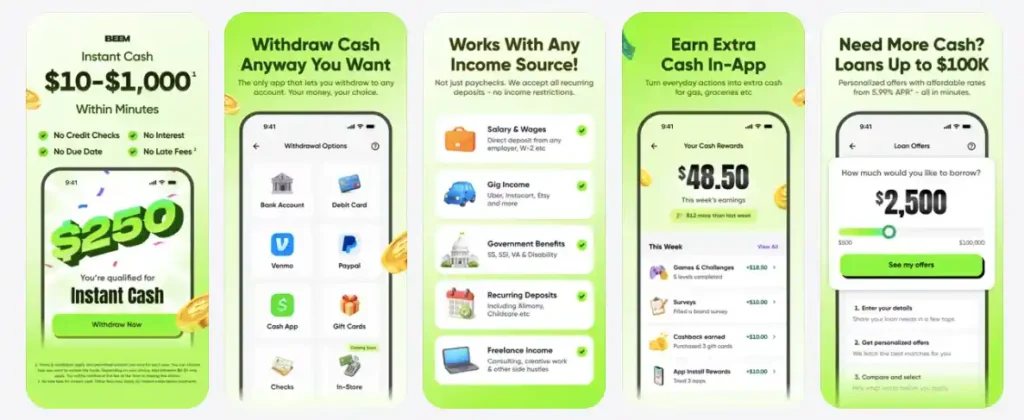
Beem is a US financial app designed for adults seeking comprehensive money management tools without age-targeted branding or restrictive limits. Full product details are available on the official website. Compared to Step, Beem serves as an alternative for adult beginners who want to build credit alongside higher cash advance limits and broader financial management features.
While Step focuses on teenagers with a free, secured card model, Beem offers the Credit Builder Card tailored for adults, without requiring parental sponsorship. Regarding liquidity access, Beem’s Everdraft™ feature offers advances up to $1,000—substantially higher than Step’s $250 EarlyPay limit—which offers greater flexibility for larger recurring expenses.
Beem also includes specialized financial management tools that Step does not focus on:
- A subscription tracker that identifies unused recurring charges. Eliminating forgotten subscriptions can optimize monthly cash flow alongside credit-building efforts.
- ACH bill coverage beyond card transactions, allowing Everdraft to assist with rent, utility, and insurance payments before payday.
- Automated budgeting tools and deal discovery features that streamline daily financial management.
Beem is a financial technology company rather than a bank. Everdraft operates without interest charges, credit checks, or fixed due dates, with individual advance limits determined by account activity.
Step vs Beem: A Quick Comparison
While both platforms support credit building and access to liquidity, they target distinct user demographics. The table below outlines key differences.
| Factor | Step | Beem |
|---|---|---|
| Built for | Teens and young adults | Adults |
| Parent sponsor required | Yes, under 18 | No |
| Credit-building card | Secured card, 3-bureau reporting | Credit Builder Card, adult-focused |
| Max cash advance | $250 (EarlyPay) | Up to $1,000 (Everdraft) |
| Covers bills via ACH | No, card and ATM only | Yes |
| Extra money tools | Basic banking | Subscription monitor, budgeting, deals |
| Monthly cost | Free basic, $4.99 Black | Plans from $1.99 |
For adult users, the choice depends on feature requirements. Adults seeking tools aligned with mature financial responsibilities may prefer Beem over youth-oriented platforms.
For managing larger expenses before payday, Beem’s $1,000 ceiling offers greater flexibility than Step’s $250 limit. Additionally, users who want integrated subscription tracking and budget monitoring alongside credit building gain broader coverage through a single platform.
Step remains an effective choice for teenagers building credit under parental supervision, while Beem caters to adult financial requirements. Selecting the appropriate app depends on your age group, credit goals, and required feature set. Download the Beem app now.
FAQs About Is Step Legit
Is Step legitimate and safe?
Yes. Step is a legitimate financial technology company serving over 6.5 million users. Accounts are FDIC-insured up to $250,000 through partner banks Evolve Bank & Trust and Stride Bank. It has maintained operations without major regulatory issues and reports activity to all three credit bureaus.
Is it true that Step helps build credit at no cost?
Yes. Step’s basic tier carries no monthly maintenance fees and reports secured card activity to Equifax, Experian, and TransUnion. Users build credit using their own funds, without incurring interest charges or accumulating debt.
Do I need a parent to use Step?
A parent or guardian sponsor is required only for users under 18. Sponsorship enables adults to monitor spending and adjust controls. Adults 18 and older can open independent accounts, though the app maintains its youth-focused design.
What is the minimum age for Step?
The minimum age to open a Step account is 13, and the account requires parental sponsorship until the user reaches age 18.
How much can my credit score go up with Step?
Step reports that average users increase their credit scores by approximately 57 points within their first year. Actual gains vary based on starting credit profiles, transaction frequency, and overall payment history, with first-time credit builders typically seeing faster results.
Why might an adult choose Beem over Step?
Beem is tailored for adults, offering higher cash advances (up to $1,000, compared to Step’s $250), direct ACH bill-pay support, subscription monitoring, and budgeting tools, without requiring parental sponsorship or using youth-targeted branding.
Final Verdict
Step is a legitimate, FDIC-insured platform that provides an effective entry point for credit building, particularly for teenagers and young adults. It’s a free basic account that minimizes financial barriers, and its secured card structure prevents debt accumulation.
However, its design targets a younger audience, which may make its interface and feature limits less suitable for older adults. The $250 cash advance limit is lower than competitors’, and the secured card model does not offer traditional credit limit increases.
For teenagers aged 13 to 18 or young adults comfortable with a youth-oriented interface, Step is a practical option. For adults who require higher limits, direct-bill coverage, and comprehensive money-management tools, Beem offers a better fit.