Key Summary
If you are researching an OppLoans debt consolidation loan, you are already taking one of the most financially sound steps available to anyone managing multiple high-interest debts simultaneously. Debt consolidation, the act of combining multiple obligations into a single structured installment loan at a lower blended interest rate, reduces monthly payment complexity, lowers total interest paid over time, and replaces the stress of managing several due dates with a single predictable payment. The question is not whether consolidation is the right strategy. For most borrowers carrying multiple high-interest balances, it almost always is. The question is whether OppLoans is the right lender to execute that strategy, or whether better rates exist elsewhere for your specific financial profile.
This guide covers exactly what OppLoans offers for debt consolidation, what the true cost of their loan products looks like, where their model creates limitations for borrowers with larger consolidation needs, and how Beem’s personal loan marketplace helps you compare personalized debt consolidation offers from multiple trusted lenders simultaneously without a single hard credit inquiry during the shopping stage.
What Is OppLoans and How Do Their Debt Consolidation Loans Work?
OppLoans, now operating as OppFi, is an online installment lender that targets near-prime and non-prime borrowers who have been declined by traditional banks and credit unions. Their core product is a fixed-rate personal installment loan that can be used for a range of purposes including debt consolidation, emergency expenses, home repairs, and major purchases.
OppLoans positions itself as a responsible alternative to payday loans by offering structured monthly installment repayment rather than a lump-sum demand on the next payday. Their loans are fully amortized, meaning each monthly payment covers both principal and interest, and the loan balance decreases with every payment made.
For debt consolidation specifically, OppLoans allows borrowers to take a single installment loan and use the proceeds to pay off multiple existing obligations including credit card balances, payday loans, and other high-interest debts. The result is a single monthly payment on a fixed schedule rather than multiple separate payments to multiple creditors each month.
OppLoans reports payment history to the major credit bureaus, which means consistent on-time payments on an OppLoans consolidation loan can contribute positively to your credit score over the repayment term. This credit-building dimension adds long-term value beyond the immediate benefit of simplified repayment.
OppLoans Debt Consolidation Loan: Rates, Amounts, and Terms
Understanding the specific parameters of OppLoans products is essential before evaluating whether they are competitive for your consolidation need.
Loan Amounts
OppLoans offers personal installment loans from $500 to $4,000 in most states, with some states allowing access to higher amounts depending on local lending regulations. For borrowers whose total debt consolidation need falls below $4,000, OppLoans can technically cover the full consolidation. For borrowers carrying $5,000, $10,000, or more in combined high-interest debt, OppLoans’ loan ceiling is a hard structural limitation that prevents them from consolidating everything into a single loan.
Interest Rates and APR
This is where the OppLoans debt consolidation loan picture requires the most careful attention. OppLoans serves near-prime and non-prime borrowers, and the interest rates on their products reflect the elevated risk of this borrower segment. APRs on OppLoans products can reach into very high territory, sometimes ranging from 59% to 160% or higher depending on the state, the borrower’s credit profile, and the specific loan product.
For debt consolidation to make financial sense, the consolidation loan rate must be lower than the blended average rate of the debts being consolidated. If you are consolidating payday loan debt at 300% effective APR, an OppLoans rate in the 100% APR range is still a meaningful improvement. But if you are consolidating credit card debt in the 24% to 29% APR range, an OppLoans consolidation loan in the 100%+ range would significantly increase your total interest burden rather than reduce it. Understanding this comparison before accepting any consolidation offer is critical.
Loan Terms
OppLoans repayment terms typically range from 9 to 18 months depending on the loan amount and state. These are relatively short terms compared to personal loan products from other lenders in the alternative lending space, which can extend to 36, 48, or 60 months. Shorter terms mean higher monthly payments for the same loan amount, which may strain budgets that are already under pressure from multiple debt obligations.
When an OppLoans Debt Consolidation Loan Makes Sense
Despite the high APR structure, there are specific scenarios where an OppLoans consolidation loan represents a genuine financial improvement for the borrower.
For borrowers consolidating payday loan debt, informal high-interest obligations, or short-term installment products with triple-digit effective APRs, moving to an OppLoans loan with a structured repayment schedule and a lower effective rate is a meaningful step in the right direction. The installment structure alone provides more predictability and repayment discipline than the rollover model of payday lending.
For borrowers who need a small consolidation loan under $4,000 and have been declined by mainstream lenders due to credit score, OppLoans may be one of the few structured installment options accessible at their current profile. In this context, the higher rate reflects the limited competition for their credit tier rather than a choice between equally available options.
For borrowers who specifically want credit bureau reporting as part of their consolidation strategy, OppLoans’ reporting to major bureaus makes consistent on-time payments a genuine credit-building activity alongside debt reduction.
Where OppLoans Falls Short for Debt Consolidation Borrowers
The limitations of OppLoans as a debt consolidation lender become significant for borrowers whose needs fall outside their narrow product parameters.
Loan Ceiling Prevents Full Consolidation for Most Borrowers
The average American carrying multiple high-interest debts is managing balances that regularly exceed $4,000 when credit cards, medical bills, and other obligations are combined. OppLoans’ $4,000 ceiling means most borrowers with genuine consolidation needs cannot consolidate all of their debt through OppLoans in a single transaction. Partial consolidation leaves some high-interest balances active, which reduces the monthly payment relief and total interest savings that make consolidation worthwhile in the first place.
Very High APRs Can Worsen the Situation for Some Borrowers
For borrowers whose existing debt carries rates in the 20% to 30% APR range, accepting an OppLoans consolidation loan at 100% or higher APR would dramatically increase their total interest cost despite simplifying their monthly payment count. Consolidation that increases your effective interest rate is not consolidation in any financially meaningful sense. It is refinancing into a worse position while reducing organizational complexity.
Short Repayment Terms Create Monthly Payment Pressure
OppLoans’ 9 to 18 month repayment window compresses the repayment timeline in a way that generates higher monthly payments for the same loan amount than lenders offering 36, 48, or 60 month terms. Borrowers who are consolidating because monthly payment pressure is already unmanageable may find that OppLoans’ shorter terms create a payment obligation that is equally or more difficult to sustain.
How Beem’s Personal Loan Marketplace Finds Better Debt Consolidation Rates
Beem’s personal loan marketplace is designed specifically to solve the core problem that makes OppLoans a suboptimal choice for many consolidation borrowers: accepting a single lender’s rate without knowing whether better options exist for your specific profile.
Compare Personalized Offers from Multiple Lenders Without a Hard Credit Inquiry
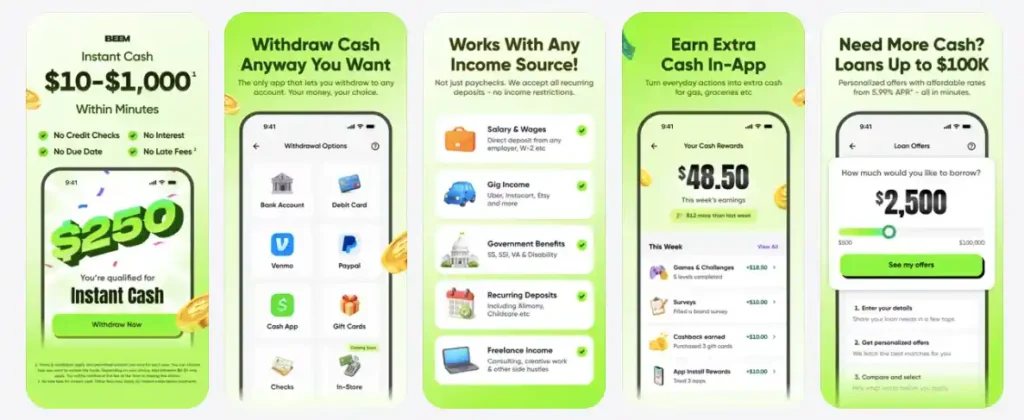
When you enter your details and consolidation loan requirements inside the Beem app, Beem generates personalized offers from multiple trusted lenders simultaneously based on your actual financial profile. This comparison process does not involve a hard credit inquiry during the shopping stage. Your credit score is completely unaffected while you review what is available.
This is fundamentally different from applying to OppLoans, receiving their offer, and then applying to a second lender to compare, which would trigger a hard inquiry at each application. Beem shows you the full landscape of available consolidation offers across multiple lenders from a single entry point, with no credit score impact during the comparison process.
Access Consolidation Loans from $500 to $100,000
Beem’s lender network covers personal and debt consolidation loans from $500 to $100,000, giving borrowers whose consolidation need exceeds OppLoans’ $4,000 ceiling a path to completing their full consolidation in a single loan. A borrower with $15,000 in combined high-interest debt who cannot consolidate everything through OppLoans can find lenders through Beem’s marketplace willing to cover the full amount at a competitive rate for their profile.
Save Up to 40% on Interest Rates Through Rate Comparison
Beem highlights that users who compare personalized offers through the marketplace before applying consistently access rates up to 40% lower than users who apply directly to a single lender without shopping. For a consolidation borrower, a 40% reduction in interest rate on a $10,000 loan over 36 months represents over $2,000 in reduced total interest paid. That is money that stays in your budget every month rather than going to a lender.
Longer Repayment Terms Lower Monthly Payment Pressure
Beem’s lender network includes options with repayment terms significantly longer than OppLoans’ 9 to 18 month window. Terms extending to 36, 48, 60, and in some cases longer months are available depending on the lender and borrower profile. Longer terms lower the monthly payment on the same loan amount, which is often the primary motivation for consolidation in the first place.
Debt Consolidation Is a Primary Use Case
Beem’s personal loan marketplace specifically positions debt consolidation as one of its core use cases, meaning the lenders in its network include those who specialize in consolidation products alongside general-purpose personal lenders. Consolidation-focused lenders often structure their offers with features specifically designed for the consolidation use case, including direct payoff to existing creditors rather than disbursement to the borrower, which removes the risk of funds being used for other purposes before debt payoff is completed.
Beem Everdraft: For Immediate Small Cash Needs Alongside Your Consolidation
Debt consolidation addresses the structural long-term cost of carrying multiple high-interest balances. But the process of applying for, getting approved for, and receiving a consolidation loan takes time. During that window, unexpected small expenses can still arise that need immediate coverage.
Beem Everdraft gives eligible users access to between $10 and $1,000 against their upcoming deposit with zero interest, no credit check, and no income restrictions. Funds arrive within minutes for eligible users. Repayment is automatic from the next verified deposit with no interest charged and no penalty fees applied.
For users who are in the process of consolidating debt through Beem’s personal loan marketplace and encounter a short-term cash need during the approval window, Everdraft provides same-day coverage without disrupting the consolidation application or adding new debt to the profile being consolidated.
The combination of Everdraft for immediate short-term needs and the personal loan marketplace for structured debt consolidation means Beem users have appropriate financial tools available for every timeline and every amount simultaneously within a single platform.
Alternatives to OppLoans for Debt Consolidation in 2026
Beyond Beem’s marketplace, several lenders serve the near-prime and non-prime consolidation borrower segment at rates that compete favorably with OppLoans for borrowers in certain credit tiers.
Avant
Avant serves borrowers with credit scores from approximately 580 upward and offers personal loans from $2,000 to $35,000 with terms from 12 to 60 months. For consolidation borrowers whose credit profile qualifies for Avant, their rates are typically more competitive than OppLoans’ highest APR range and their loan ceiling is substantially higher. Avant’s administration fee structure affects APR calculations and should be factored into any direct comparison.
LendingPoint
LendingPoint serves borrowers from approximately 585 credit score upward and uses a broader underwriting model that incorporates employment history and cash flow data alongside credit score. Their loan range from $2,000 to $36,500 with terms up to 72 months covers a wider consolidation range than OppLoans and their longer term options reduce monthly payment pressure more effectively.
Upstart
Upstart’s AI-powered underwriting model considers education, employment, and income data alongside credit history, which can produce approval and rate outcomes for borrowers that traditional credit score models would price much higher. Loan amounts from $1,000 to $50,000 with next-business-day funding cover a much wider consolidation range than OppLoans at potentially more competitive rates for borrowers with strong employment or education profiles despite limited credit history.
Rise Credit
Rise Credit operates in the same near-prime installment space as OppLoans but offers a rate reduction program for customers who maintain consistent on-time payment records. This means borrowers who start at a higher rate can reduce their effective rate progressively over the repayment term, which is a genuine incentive structure for responsible repayment that OppLoans does not match.
How to Decide Between OppLoans and Beem for Debt Consolidation
The decision framework is straightforward when you reduce it to the key variables.
If your consolidation need is under $4,000 and you have been declined by every other lender, OppLoans may be one of the few accessible structured options. Use it as a stepping stone, repay on time to build credit, and plan to refinance at a better rate once your credit profile improves.
If your consolidation need exceeds $4,000, OppLoans cannot cover your full requirement regardless of their rate. Beem’s marketplace is the appropriate starting point.
If you are unsure whether OppLoans is offering a competitive rate for your profile, use Beem’s marketplace to generate comparison offers before applying to OppLoans. The comparison is free, takes minutes, and does not affect your credit score. If Beem surfaces better rates, you save money. If OppLoans turns out to be competitive for your profile, you have confirmed that with data rather than assumption.
If your consolidation need is alongside an immediate small cash need, use Beem Everdraft for the immediate requirement and Beem’s marketplace for the structured consolidation loan, keeping both tools inside a single platform.
Frequently Asked Questions
What Is an OppLoans Debt Consolidation Loan and How Does It Work?
An OppLoans debt consolidation loan is a fixed-rate personal installment loan from OppFi that allows borrowers to combine multiple existing debts into a single monthly payment. OppLoans serves near-prime and non-prime borrowers with loan amounts up to $4,000 in most states and repayment terms from 9 to 18 months. APRs on OppLoans products can be very high depending on the borrower’s credit profile and state, making rate comparison against competing lenders an essential step before accepting their offer.
Is OppLoans a Good Choice for Debt Consolidation?
OppLoans can be appropriate for borrowers consolidating very high-interest obligations like payday loans or informal debts where their rate represents a genuine improvement on the existing blended rate. For borrowers consolidating standard credit card debt in the 20% to 30% APR range, OppLoans’ higher rate structure may worsen the total interest burden despite simplifying monthly payments. Comparing OppLoans against competing lenders through Beem’s marketplace before applying is the most reliable way to determine whether their offer is competitive for your specific profile.
How Can Beem Help Me Find a Better Debt Consolidation Rate Than OppLoans?
Beem’s personal loan marketplace generates personalized debt consolidation offers from multiple trusted lenders simultaneously based on your financial profile, without performing a hard credit inquiry during the comparison stage. You see available rates, monthly payments, and total repayment costs across multiple lenders side by side before committing to any application. Users who compare through Beem before applying consistently access rates up to 40% lower than users who apply directly to a single lender without shopping.
What Is the Maximum Amount I Can Borrow for Debt Consolidation Through Beem?
Beem’s personal loan marketplace covers consolidation loans from $500 to $100,000 depending on your eligibility and the lenders whose offers match your profile. This range is significantly broader than OppLoans’ typical ceiling of $4,000, making Beem’s marketplace appropriate for borrowers with larger total debt balances that OppLoans cannot fully consolidate in a single transaction.
Does Comparing Debt Consolidation Rates Through Beem Hurt My Credit Score?
No. Beem’s personal loan rate comparison process does not involve a hard credit inquiry at the shopping stage. You can generate personalized offers from multiple lenders, compare rates, terms, and monthly payment amounts, and evaluate your full range of options without any impact to your credit score. A hard inquiry only occurs if you formally apply to a specific lender after reviewing and selecting the offer you want to proceed with.