


Key Summary
Building credit from scratch is one of the most common financial obstacles for people entering adult financial life. Traditional credit cards reject applicants without existing score, and secured cards require upfront deposits that many new borrowers simply do not have. The result is a catch-22: you need credit to get credit, and there is no obvious entry point.
According to the CFPB, payment history accounts for the largest share of most credit scoring models, making consistent on-time payments the single most important behavior for anyone trying to build or repair a credit profile. Beem’s Credit Builder Card is designed to generate that payment history without requiring a deposit, a hard credit check, or any borrowing.
This guide explains how it works, who it is best suited for, how it compares to alternatives, and how to get started.
What Is the Beem Credit Builder Card
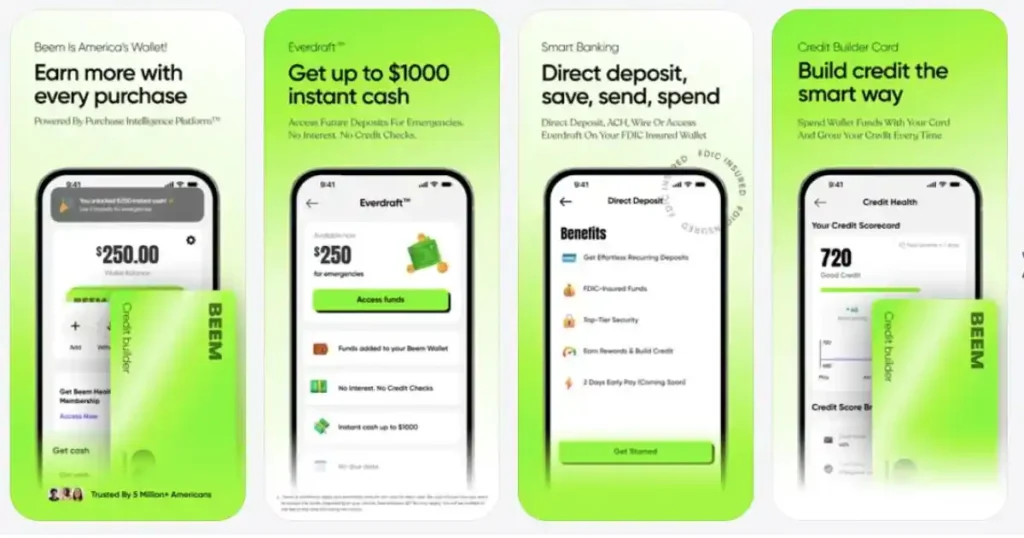
The Beem Credit Builder Card is a debit-linked credit-building product that lets users build a real credit history using their own money. It connects to your Beem Smart Wallet, which holds your funds. Each purchase made with the card is reported to all three major credit bureaus: Equifax, Experian, and TransUnion. You are not borrowing anything, so there is no interest, no debt accumulation, and no risk of a missed payment caused by an unexpected charge.
The key distinction from a traditional credit card is that you are spending money you already have, not money you are borrowing from the issuer. Credit bureaus’ reporting is significant to creatingg a credit-building benefit. Every transaction reported as paid on time adds a positive data point to your credit file, which is exactly how credit scores are built over time regardless of the credit product used.
Why Traditional Credit Options Do Not Work for Beginners
First-time borrowers face a structural problem with most mainstream credit products. The people who need credit building the most are often the least able to access the tools designed for it. Understanding why helps clarify what makes alternatives like Beem’s credit builder practically useful rather than just theoretically appealing.
Traditional unsecured credit cards require a credit score at the point of application. If you have no credit history, you have no score, and most issuers decline the application outright. The referral to a secured card is the typical outcome, but secured cards require a cash deposit ranging from $200 to $500 that serves as the credit limit. For a person who does not have $200 to $500 to lock up as collateral, a secured card is not actually accessible even though it is marketed as the entry-level option.
Credit builder loan products like those offered by Self require monthly payments into a savings account over a defined term. The loan is reported monthly as an installment account, which builds up the payment history. The drawback is that you do not access the money until the loan is paid off, and the monthly payment is a fixed obligation regardless of your cash flow situation that month.
Subscription-based products like Kikoff offer a small revolving credit line used to pay a Kikoff subscription, reported to all three bureaus for a flat monthly fee. This works, but the credit line is small and the product doesn’t offer cash access alongside the credit building.
The barriers these products collectively create include no credit history, denials due to low or nonexistent scores, required deposits or locked savings, monthly payment obligations, and monthly subscription fees just to access the reporting. Beem removes most of these barriers by linking reporting directly to purchases from your own funded wallet rather than requiring any of the above.
Also Read: Credit Building Banking App: 5 Things to Look For
How Beem Helps First-Time Borrowers Build Credit
Beem’s approach to credit building is structurally different from most alternatives. Instead of creating a new debt obligation or locking your money into a savings product, it reports your existing spending activity to the credit bureaus. The result is positive payment history generated from everyday purchases rather than from a separate financial obligation you have to manage and fund each month.
No Credit Check Required
Beem does not perform a hard credit check when you apply for the Credit Builder Card. A hard inquiry reduces your credit score and remains on your credit file for two years. For someone with a thin file or no score, an unnecessary hard inquiry is a real cost. Beem’s no-check approach means anyone can apply and start building credit immediately after funding their Beem Smart Wallet, regardless of their starting credit position.
No Interest or Monthly Fees
The Credit Builder Card charges no interest and no monthly fee. You are spending money from your wallet, not borrowing from a line of credit, so no balance that accrues interest. Other credit-building products in this category, including secured cards with maintenance fees and subscription-based products like Kikoff at $5 per month, carry ongoing costs that accumulate over months to see meaningful credit improvement. Beem’s fee-free structure removes that cost entirely.
Reports to All Three Major Credit Bureaus
Each transaction is reported to Equifax, Experian, and TransUnion. Reporting to all three bureaus matters because different lenders pull from different bureaus when evaluating applications. A credit file that appears at all three bureaus is a complete credit file, which improves your standing regardless of which bureau a future lender checks. Some credit building products report to only one or two bureaus, which leaves gaps in your profile that matter when it counts.
Debit-Linked System Prevents Debt Accumulation
Because the card draws from your Beem Smart Wallet rather than a credit line, you cannot spend money you do not have. This structure eliminates the risk of accumulating interest charges or carrying a balance that grows over time. The CFPB has documented that consumers who carry revolving credit card balances are more likely to face financial difficulty, which is the outcome a credit builder product should help people avoid. Beem’s wallet-linked structure addresses this directly.
Beem Credit Builder vs Other Credit Tools
Choosing between credit-building products depends on what you need alongside your credit history: cash access, low monthly cost, flexibility, or a specific type of credit account. The table below compares Beem to the most commonly recommended alternatives.
| Feature | Beem Credit Builder | Secured Credit Card | Self | Kikoff | Chime Credit Builder |
| Credit Check Required | No | Yes (usually) | No | No | No (with direct deposit) |
| Monthly Fee | None | Varies ($0 to $35) | $25 setup fee | $5/month | None |
| Interest Charged | None | Yes on balances | None | None | None |
| Deposit Required | No | Yes ($200 to $500) | No | No | No |
| Bureau Reporting | All three | All three | All three | All three | All three |
| Cash Access | Yes (Everdraft) | No | No | No | Limited overdraft |
| Best For | First-time, no deposit | Some credit history | Installment history | Passive reporting | Beginners with direct deposit |
Self-reports instalment payment history to all three bureaus. Monthly payments go into a Certificate of Deposit and you receive the funds at the end of the term minus fees. The $25 setup fee and fixed monthly payment make it structured but less flexible than a spending-linked product.
Kikoff provides a small revolving line of credit used to pay a $5 monthly subscription, reported to all three bureaus. It is passive and low-cost but provides no cash access. Chime‘s Credit Builder secured card is linked to spending from a Chime account balance, requires qualifying direct deposit to activate, and charges no interest or annual fee. It is structurally similar to Beem but limited to Chime account holders.
Features That Make Beem Practical for Beginners
Beyond the credit-building mechanism itself, Beem includes tools that address the practical financial challenges that accompany the early credit-building period for most users.
Instant Cash with Everdraft
Beem includes access to Everdraft, an instant cash advance feature that provides up to $1,000 with no fees and no credit check. For users building credit because their financial situation is tight, having a cash access tool alongside the credit builder eliminates the need to maintain separate products for different needs. An unexpected expense that would otherwise derail the credit building effort can be covered without taking on high-interest debt.
Smart Wallet with FDIC Insurance
The Beem Smart Wallet is FDIC insured up to the standard limit through Beem’s banking partners. It functions as a checking account with smarter tracking and reporting tools. The wallet holds the funds that power the credit builder card and provides a single account for spending, tracking, and building credit simultaneously.
AI Financial Tools
Beem’s app includes AI-powered tools for budgeting, deal finding, price comparison, and gig income discovery. For first-time borrowers who are learning to manage money alongside building credit, these tools provide context and guidance that a standalone credit card cannot. Knowing your spending patterns and upcoming obligations helps prevent the missed payments that damage credit scores most severely, since payment history is the most heavily weighted scoring factor according to CFPB guidance.
Who Should Use the Beem Credit Builder
Beem is well suited for people who need to build credit without a deposit, a monthly fee, or a new debt obligation. College students and young adults entering the workforce for the first time are the clearest fit, since they typically have no credit history and limited cash available for a secured card deposit.
Freelancers and gig workers with irregular income benefit from the wallet-linked structure since there is no fixed monthly payment to miss. New immigrants establishing a US credit profile benefit from the no-credit-check approval and tri-bureau reporting. Anyone rebuilding after a financial setback, such as a period of unemployment or a medical emergency that led to missed payments, can also use Beem to start accumulating positive history without the risk of adding new debt to an already stretched financial situation.
You do not need a cosigner, employer verification, or minimum income. You need the Beem app and a willingness to use the card for regular purchases over a sustained period.
How to Start Using the Beem Credit Builder Card
Getting started takes minutes rather than days. The process is fully digital with no branch visit, mailed card wait, or deposit transfer required.
Download the Beem app from the App Store for iOS or the Google Play Store for Android. Create your account by entering basic personal information including your name, email, phone number, and date of birth. No credit check runs at this stage. Set up your Beem Smart Wallet, which serves as the central account for your funds and card activity. Add funds to your wallet via bank transfer or direct deposit.
Activate your Credit Builder Card within the app. The card is immediately available for digital use after activation and can be used anywhere debit cards are accepted. Start using the card for everyday purchases like groceries, transportation, and subscriptions. Each purchase generates a reportable transaction that contributes to your credit history. Monitor your credit score and transaction history through the app to track progress and catch any issues early.
Check your credit reports annually at annualcreditreport.com to confirm your Beem activity is appearing correctly across all three bureaus and to identify any errors that might be reducing your score.
Frequently Asked Questions
Is Beem Credit Builder a real credit card?
No. The Beem Credit Builder Card is a debit-linked credit building product that draws from your Beem Smart Wallet rather than a line of credit. It works like a debit card operationally but reports activity to all three major credit bureaus, which is what generates the credit-building benefit without any debt accumulation or interest charges.
Will applying for the Beem Credit Builder hurt my credit score?
No. Beem does not perform a hard credit check when you apply. Hard inquiries temporarily lower your credit score and stay on your file for two years. Because Beem skips this step entirely, applying carries zero credit score impact regardless of your current score or the length of your existing credit history.
How long does it take to see credit score improvement?
Most users begin to see score changes within 30 to 60 days of consistent card use, since that is the typical credit bureau update cycle. Meaningful improvement generally takes six to twelve months of regular on-time activity. The CFPB notes that payment history is the most heavily weighted scoring factor, so consistency matters more than speed.
Are there any fees on the Beem Credit Builder Card?
No. There is no monthly fee, annual fee, transaction fee, or interest charge. You spend your own money from the wallet, so there is no balance to charge interest on. This fee-free structure differentiates Beem from secured cards with maintenance fees and subscription-based products like Kikoff that charge $5 per month for access.
How does credit utilization affect my score and how do I keep it low?
Credit utilization is your current balance divided by your total available credit on revolving accounts. Keeping it below 30% is the standard guidance, but below 10% produces stronger scores. Pay down balances before your statement closes since that is when most issuers report your balance to the bureaus.
What is the difference between building credit and repairing credit?
Building credit means establishing a file from scratch with no existing history. Repairing credit means improving a score damaged by missed payments, collections, or high utilization. The tools overlap significantly, but repair also requires disputing errors and waiting for negative items to age off your file over time.
When is the right time to apply for an unsecured credit card after using a credit builder?
Most lenders look for at least 6 months of credit history and a score above 620 to 640 before approving entry-level unsecured cards. After 12 months of consistent on-time activity with a credit-builder product, many users qualify for at least one unsecured card, which further expands available credit and improves overall utilization ratios.
Conclusion
The Beem Credit Builder Card gives people with no credit history a practical, zero-cost path into the credit system. No deposit, no credit check, no monthly fee, no debt. Each purchase from your funded wallet generates a reported on-time payment that builds your file at all three bureaus simultaneously. Over six to twelve months of consistent use, that activity accumulates into a credit profile that opens access to credit cards, loans, and better rates on insurance and housing.
Credit building is not fast, but it is straightforward when the right product is in place. Beem is a practical starting point for that process, and the Everdraft cash access feature means you are not trading financial flexibility for a credit score on paper.





















