Key Summary
If you are searching for banks like NetCredit, you are looking for something specific. You want a lender that approves borrowers outside the narrow prime credit range, moves fast, does not require perfect employment history, and offers a structured installment repayment schedule rather than the lump-sum trap of a payday loan. That is exactly the gap NetCredit was built to fill, and it is the same gap that dozens of competing lenders, fintech platforms, and personal loan marketplaces are now competing to serve with better rates, broader accessibility, and smarter technology.
The near-prime and non-prime personal loan market has expanded dramatically in 2026. Borrowers who were previously left with payday loans as their only option now have access to legitimate installment lenders, AI-powered loan marketplaces, and instant cash advance tools that cost a fraction of what the previous generation of alternative lending charged. Understanding what separates a good option from a predatory one, and knowing which platforms genuinely compare across multiple lenders before showing you an offer, is the difference between finding a loan that helps your financial situation and accepting one that makes it worse.
This guide covers what NetCredit offers, why borrowers look for alternatives, what the best banks like NetCredit look like in 2026, and how Beem’s personal loan marketplace gives you the fastest and most cost-effective way to compare personalized offers across multiple lenders without a single hard credit inquiry during the shopping stage.
What Is NetCredit and Who Uses It
NetCredit is an online personal loan and line of credit provider owned by Enova International, one of the largest alternative lending companies in the United States. NetCredit specifically targets near-prime and non-prime borrowers, people whose credit scores fall below the threshold where traditional banks and credit unions will approve them but who are not in the deepest subprime category.
NetCredit offers personal loans ranging from $1,000 to $10,000 depending on state, with loan terms that vary by location and product type. They also offer lines of credit as an alternative to installment loans in states where that product is available. NetCredit’s primary competitive advantages are its willingness to lend to borrowers with lower credit scores and its fully online application and funding process, which can deliver funds within one business day of approval.
The borrowers who most commonly use NetCredit include people with credit scores between 550 and 660 who have been declined by traditional banks, those with limited credit history who cannot access mainstream credit products, borrowers consolidating high-interest payday loan debt into a structured installment schedule, people facing unexpected emergency costs who need fast access to several thousand dollars, and individuals rebuilding their credit through consistent on-time installment loan payments.
Why People Search for Banks Like NetCredit
The volume of searches for banks like NetCredit reflects a real market need. Borrowers who have used NetCredit before or who are researching it for the first time typically search for alternatives for several consistent reasons.
NetCredit APRs Can Be Very High
NetCredit’s interest rates reflect the elevated risk of lending to near-prime and non-prime borrowers. APRs on NetCredit products can reach into very high double-digit territory depending on the borrower’s credit profile, the state, and the specific product. For borrowers with scores toward the lower end of NetCredit’s eligibility range, the effective cost of borrowing can be substantially higher than what competing lenders in the same space charge for an identical loan amount and term.
Limited Loan Amounts Cap What Borrowers Can Access
NetCredit’s loan maximum of $10,000 in most states is insufficient for borrowers who need larger amounts for debt consolidation, significant home repairs, major medical bills, or other substantial financial needs. Borrowers who outgrow NetCredit’s loan ceiling quickly discover that the alternative lending market includes lenders willing to offer significantly more at competitive rates.
State Availability Restrictions
NetCredit does not lend in all states. Borrowers in states where NetCredit is unavailable need alternative lenders that serve their location while offering a similar or better product structure.
Desire to Compare Before Committing
Increasingly, borrowers searching for banks like NetCredit are not dissatisfied with NetCredit specifically. They are financially savvy enough to know that accepting the first personal loan offer received is almost never the most cost-effective decision. They want to compare NetCredit’s offer against competitors before clicking apply on anything, which is exactly the right instinct and the reason multi-lender comparison platforms have become so valuable.
What to Look For in Banks Like NetCredit
Evaluating alternative lenders fairly requires assessing the same variables across every option rather than comparing headline loan amounts or brand names. Here are the factors that genuinely determine whether a lender is appropriate for your situation.
Interest Rates and APR
The annual percentage rate is the single most important number to compare across lenders. APR includes both the stated interest rate and any origination fees, giving you a true cost of borrowing that makes direct comparison between offers possible. A lender with a lower stated rate but a 5% origination fee may carry a higher APR than a lender with a slightly higher stated rate and no origination fee. Always compare APR, not just the headline interest rate.
Loan Amounts and Terms
Match the lender’s available loan range to your specific need. A lender that offers $1,000 to $10,000 is not useful if you need $15,000. A lender that offers 12 to 60 month terms is not useful if your budget requires a 72 or 84 month repayment schedule to keep monthly payments manageable. Identify your target loan amount and preferred term before evaluating any specific lender.
Credit Requirements and Eligibility
Alternative lenders vary significantly in their minimum credit score requirements, income verification standards, and account history requirements. Understanding where each lender’s eligibility floor sits helps you avoid applying to lenders who will decline your profile, which wastes a hard credit inquiry. Using a comparison platform that matches your profile to appropriate lenders before triggering any hard inquiry is significantly more efficient than applying sequentially to individual lenders.
Speed of Funding
For borrowers with urgent financial needs, funding timeline is a critical variable. Some alternative lenders fund within one business day of approval. Others take two to five business days. For immediate needs, the funding speed difference between lenders matters as much as the interest rate difference. For immediate needs under $1,000 where a personal loan timeline is too slow, an instant cash advance tool like Beem Everdraft delivers funds within minutes rather than days.
Fees and Transparency
Origination fees, late payment fees, prepayment penalties, and administrative charges all add to the total cost of a personal loan beyond the stated interest rate. Responsible alternative lenders disclose all fees clearly in their loan agreements. Predatory lenders bury fees in fine print that only becomes visible after the loan is accepted. Always read the full fee disclosure before signing any loan agreement.
Best Banks and Lenders Like NetCredit in 2026
The alternative personal loan market includes several platforms worth considering alongside NetCredit when comparing options for near-prime and non-prime borrowers.
OppFi
OppFi is one of the most recognized names in the near-prime personal loan space. They offer installment loans to borrowers with limited credit history or fair credit scores, with a focus on fast application processing and same-day or next-business-day funding. OppFi reports payment history to all three major credit bureaus, making their loans useful for credit building alongside their primary function as emergency financing. APRs on OppFi loans are high relative to prime lending but the product is structured as a genuine installment loan with predictable monthly payments.
Avant
Avant operates further up the credit spectrum than NetCredit, serving borrowers with credit scores from approximately 580 upward. They offer personal loans from $2,000 to $35,000 with terms from 12 to 60 months, covering a wider loan amount range than NetCredit. Avant’s APRs are more competitive for borrowers in the 600 to 700 credit score range than most near-prime lenders, and their application process is fully online with funding possible as fast as the next business day. Avant also charges an administration fee rather than a traditional origination fee, which affects APR calculations when comparing against other lenders.
LendingPoint
LendingPoint serves borrowers with credit scores from approximately 585 upward and offers personal loans from $2,000 to $36,500 with terms from 24 to 72 months. Their underwriting model uses data points beyond traditional credit scores, including employment history and cash flow patterns, which can benefit borrowers whose credit scores underrepresent their true repayment capacity. LendingPoint funds as fast as the next business day and charges origination fees that vary by state and borrower profile.
Rise Credit
Rise Credit, operated by Elevate Credit, is a direct competitor to NetCredit in the near-prime installment loan space. They offer loans from $500 to $5,000 depending on state with a specific focus on borrowers rebuilding their credit. Rise reports payment history to at least one credit bureau and offers rate reduction programs for customers who maintain consistent on-time payment records, meaning responsible borrowers can reduce their effective rate over the life of the loan. APRs start high but the reduction program provides a genuine incentive structure for repayment discipline.
Possible Finance
Possible Finance offers smaller short-term installment loans typically up to $500, structured as biweekly payment products that report to credit bureaus. They specifically target borrowers with very thin or damaged credit histories as a stepping stone between payday loan products and full installment lending. Their loan amounts are smaller than NetCredit’s and the product is designed for credit building rather than large-scale borrowing, making them an appropriate option for borrowers in the earliest stages of credit recovery.
Upstart
Upstart operates further up the credit spectrum than most lenders in this list but is worth including because their AI-powered underwriting model approves borrowers that traditional credit score models would decline. They offer personal loans from $1,000 to $50,000 and use education, employment, and income data alongside credit history to generate offers. For borrowers who sit in the fair-to-good credit range with strong income and employment profiles, Upstart often produces significantly more competitive rates than NetCredit-tier lenders. Funding is available within one business day of acceptance.
Mariner Finance
Mariner Finance offers personal loans both online and through physical branch locations, which differentiates them from most alternative digital lenders. Loan amounts range from $1,000 to $25,000 depending on state and borrower profile, and they accept secured personal loans using collateral for borrowers who want better rates in exchange for asset backing. Mariner’s physical locations can be useful for borrowers who prefer in-person service alongside digital applications, and they serve a wide range of credit profiles across their near-prime and non-prime lending products.
Beem Personal Loan Marketplace: The Smarter Way to Find Banks Like NetCredit
Every lender listed above serves a real borrower need. But applying to each of them individually to find the best rate is an inefficient, credit-damaging process that most borrowers do not have the time or score cushion to pursue. This is exactly the problem Beem’s personal loan marketplace solves.
Compare Personalized Rates Across Multiple Lenders Without a Hard Credit Inquiry
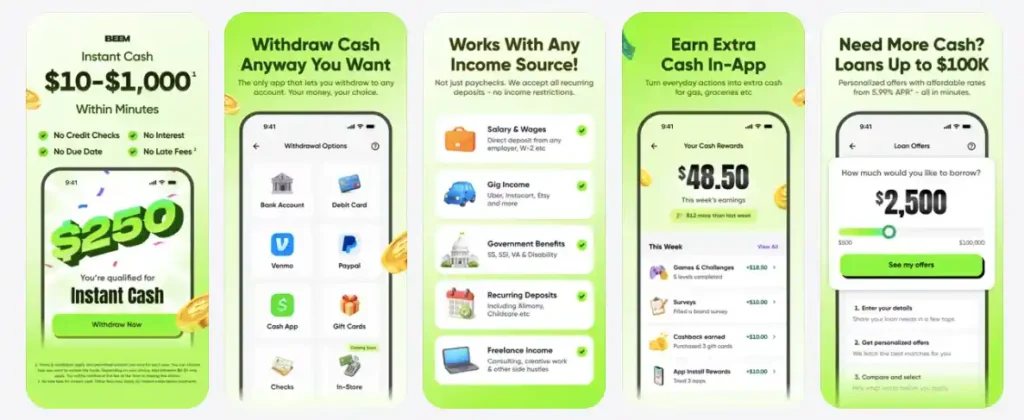
When you enter your loan requirements and personal details inside the Beem app, Beem generates personalized offers from multiple trusted lenders simultaneously based on your actual financial profile. The initial comparison process does not involve a hard credit inquiry. Your credit score is completely unaffected while you review available offers, compare rates and terms, and evaluate monthly payment amounts across lenders.
This is the structural advantage that makes Beem’s marketplace fundamentally different from visiting NetCredit, then Avant, then LendingPoint individually. Each direct application potentially triggers a hard inquiry. Beem shows you the full comparison without a single hard inquiry until you choose the specific offer you want to proceed with.
Access Loans from $500 to $100,000
Beem’s lender network covers personal loans from $500 for smaller immediate needs up to $100,000 for major financial goals including debt consolidation, home improvement, medical expenses, and large one-time purchases. This range is significantly broader than NetCredit’s $10,000 ceiling, meaning borrowers who need more than NetCredit can offer find appropriate options through Beem’s marketplace without needing to identify and evaluate individual lenders separately.
Save Up to 40% on Interest Rates Through Rate Comparison
Beem highlights that users who compare personalized offers through the marketplace before applying consistently access rates up to 40% lower than users who accept the first offer they receive by applying directly to a single lender. On a $10,000 personal loan over 48 months, a 40% interest rate reduction represents well over $1,500 in reduced total repayment cost. On a $20,000 debt consolidation loan, the savings from comparison are proportionally larger and represent real money that stays in your budget.
Debt Consolidation at Lower Rates
For borrowers who are managing multiple high-interest debts including credit card balances, payday loans, and informal obligations simultaneously, Beem’s marketplace is specifically designed to find the most competitive debt consolidation offer available across its lender network. Consolidating into a single structured personal loan at a lower blended rate reduces monthly payment complexity and total interest cost simultaneously, which is the exact outcome most near-prime borrowers searching for banks like NetCredit are trying to achieve.
No Income Restrictions or Minimum Employment Requirements at the Shopping Stage
Beem’s comparison process does not require you to meet specific income thresholds or employment minimums before generating offers. You enter your details, Beem surfaces what is available at your current profile, and you evaluate what is appropriate before making any commitment. This approach respects the borrower’s time and credit profile rather than forcing trial-and-error applications to find which lenders will approve which profiles.
Beem Everdraft: When You Need Cash Faster Than Any Personal Loan Can Deliver
For borrowers whose need is immediate and under $1,000, the personal loan application process, regardless of how fast the lender funds, may be too slow. A car that needs to be running tomorrow morning does not benefit from a next-business-day funding promise if the application, approval, and funding steps together take until the day after.
Beem Everdraft gives eligible users access to between $10 and $1,000 against their upcoming deposit with zero interest, no credit check, and no income restrictions. Funds arrive within minutes of completing the request inside the Beem app. Repayment is fully automatic when the next verified deposit arrives in the linked account. There are no rollover fees, no penalty charges, and no interest accruing in the background. The exact amount borrowed is the exact amount recovered at repayment.
For urgent needs under $1,000, Beem Everdraft is faster, cheaper, and structurally simpler than any personal loan product from NetCredit or any competing lender in the alternative lending space. It requires no application, no credit review, and no funding timeline. It bridges the gap between now and the next deposit at zero cost beyond the borrowed principal.
Many Beem users use both tools at different times. Everdraft covers immediate small-amount timing gaps week to week. The personal loan marketplace handles larger structured borrowing needs with longer repayment timelines. Having both available inside the same platform means the appropriate financial tool is always accessible regardless of the size or urgency of the need.
Tips to Improve Your Approval Odds at Banks Like NetCredit
Several practical steps improve both your approval probability and the interest rate you are offered at any alternative lender, including those surfaced through Beem’s marketplace.
Check your credit report before applying and dispute any errors or outdated negative items. Incorrect negative information on your credit report artificially suppresses your score below where it should sit, and removing errors can produce a meaningful score improvement within 30 to 60 days without any change in your actual financial behavior.
Pay down credit card balances below 30% of your available credit limit before applying for any installment loan. Credit utilization is one of the most heavily weighted factors in credit score calculation, and reducing it even modestly in the weeks before applying can meaningfully improve the rate offered.
Document all income sources comprehensively when completing any loan application. Gig earnings, freelance income, benefit payments, and part-time wages all count toward your total income profile and may be the difference between approval and decline at lenders who review income alongside credit history.
Use Beem’s personal loan marketplace to understand what is available at your current profile before submitting any formal application. Knowing your realistic rate range prevents you from accepting the first offer received simply because you did not know better options exist.
If you hold assets including a vehicle, savings account balance, or other property, consider whether a secured personal loan at a lower rate is appropriate for your borrowing need. Offering collateral reduces lender risk and typically translates into a better rate for the same credit profile.
How to Decide Between Banks Like NetCredit and Beem’s Marketplace
The decision framework is straightforward when reduced to the key variables.
If your loan need is under $1,000 and you need money within minutes, Beem Everdraft is the right tool. No lender in the alternative loan space funds faster at zero interest.
If your loan need is between $1,000 and $10,000 and you want to ensure you are accessing the most competitive rate available for your credit profile before committing, use Beem’s personal loan marketplace to compare offers including those from NetCredit-tier lenders before choosing.
If your loan need exceeds $10,000, NetCredit’s $10,000 ceiling makes it structurally unable to serve your requirement regardless of their rate. Beem’s marketplace surfaces lenders covering up to $100,000, making it the appropriate starting point for larger borrowing needs.
If debt consolidation is your primary goal, Beem’s marketplace specifically positions debt consolidation as a core use case and generates offers from lenders who specialize in consolidation products alongside those who focus on general-purpose personal loans.
In every scenario where a personal loan above $1,000 is the appropriate tool, comparing through Beem’s marketplace before applying anywhere directly is the financially rational first step. It protects your credit score during the shopping phase, shows you the full range of available offers simultaneously, and consistently produces better rates than single-lender direct applications.
Building Long-Term Financial Stability Beyond Alternative Lending
Borrowers who use banks like NetCredit for emergency or short-term needs often want a path toward the prime lending market where rates are significantly lower and loan amounts are significantly higher. Beem’s ecosystem supports this progression in practical ways that work alongside borrowing rather than in opposition to it.
Consistent on-time repayment of any installment loan including those from NetCredit or Beem’s marketplace lender network builds positive payment history, which is the single most influential factor in long-term credit score improvement. Every on-time payment on a structured installment loan is a positive data point reported to the credit bureaus that slowly moves your score toward the prime range where better rates become available.
Beem’s Companion Card builds credit through every transaction including ATM withdrawals and everyday purchases, adding a second positive credit-building channel alongside installment loan payment history. The Rewards Hub generates cashback from 3,000+ merchants that builds a Beem Wallet balance reducing future out-of-pocket costs. And the high-yield savings account at 5% APY gives borrowers a place to build the emergency savings buffer that reduces future reliance on alternative lending altogether.
The combination of responsible installment loan repayment, credit-building card usage, passive cashback accumulation, and competitive savings growth creates a compounding improvement in financial stability over 12 to 24 months that meaningfully reduces the cost of future borrowing.
Frequently Asked Questions
What Are the Best Banks Like NetCredit for Near-Prime Borrowers in 2026?
The strongest alternatives to NetCredit for near-prime borrowers in 2026 include Avant for loan amounts up to $35,000, LendingPoint for borrowers with data-rich profiles that underperform on traditional credit scores, Rise Credit for credit-building installment loans with rate reduction programs, Upstart for borrowers with strong employment and education profiles, and Beem’s personal loan marketplace which compares offers from multiple trusted lenders simultaneously without a hard credit inquiry during the shopping stage.
Does Beem’s Personal Loan Marketplace Include Lenders Like NetCredit?
Beem’s personal loan marketplace surfaces personalized offers from multiple trusted lenders covering the same borrower segments that NetCredit serves. The comparison process generates offers from lenders across the near-prime and broader personal loan space simultaneously, giving borrowers a benchmark to evaluate whether any specific lender’s offer is competitive for their profile before committing to a formal application.
How Much Can I Borrow Through Beem’s Personal Loan Marketplace Compared to NetCredit?
NetCredit offers up to $10,000 in most states. Beem’s personal loan marketplace covers loans from $500 to $100,000 depending on your eligibility and the lenders whose offers match your profile. For borrowers who need more than NetCredit can provide, Beem’s marketplace surfaces lenders able to serve significantly larger loan needs through the same comparison process.
What Is the Fastest Way to Get Cash If Banks Like NetCredit Are Too Slow?
For immediate cash needs under $1,000, Beem Everdraft delivers funds within minutes with zero interest, no credit check, and no income restrictions. Repayment is automatic when the next verified deposit arrives. This makes Everdraft significantly faster than any personal loan application process including NetCredit’s next-business-day funding timeline for borrowers who need money the same hour rather than the next day.
Does Comparing Loan Offers Through Beem Hurt My Credit Score?
No. Beem’s personal loan marketplace comparison process does not involve a hard credit inquiry at the shopping stage. You can generate personalized offers from multiple lenders, compare rates, terms, and monthly payment amounts, and evaluate your options in full without any impact to your credit score. A hard inquiry only occurs if you formally apply to a specific lender after reviewing and selecting the offer you want to proceed with.
Can I Use a Personal Loan from Banks Like NetCredit to Consolidate Debt?
Yes. Debt consolidation is one of the most common and financially sound uses for near-prime personal loans. Combining multiple high-interest credit card balances or payday loan obligations into a single installment loan at a lower blended rate reduces monthly payment complexity and total interest cost. Beem’s marketplace specifically highlights debt consolidation as a primary use case and generates competing offers from lenders specializing in consolidation products, which typically produces better rates than lenders focused solely on general-purpose personal borrowing.
What Is the Difference Between a Secured and Unsecured Personal Loan at Banks Like NetCredit?
An unsecured personal loan does not require collateral and is approved based on your creditworthiness and income alone. A secured personal loan requires you to offer an asset such as a vehicle or savings balance as collateral, which reduces the lender’s risk and typically produces a lower interest rate for the same credit profile. NetCredit’s primary products are unsecured installment loans. Some alternative lenders including Mariner Finance offer secured options for borrowers who want better rates in exchange for collateral backing. Beem’s personal loan marketplace surfaces both secured and unsecured offers based on your stated profile and preferences.