Key Summary
Klarna is everywhere. You see that pink button at checkout on thousands of sites, from Target to H&M, which makes many shoppers stop and ask: Is Klarna legit? The short answer is yes. Klarna is a real, regulated financial company used by more than 150 million people worldwide, and its buy now, pay later (BNPL) plans work as advertised.
The longer answer matters more for your wallet. Klarna is legit, but it is not risk-free. Most Klarna plans are interest-free if you pay on time. However, late fees add up fast, missed payments show up on your credit report, and one-click checkout makes it easy to stack purchases you cannot really afford. This guide explains what Klarna is, whether it is safe, what it actually costs, how it affects your credit, five tips for using it safely, and where Beem fits when you need cash instead of another payment plan.
What Is Klarna and How It Works
Klarna is a Swedish company founded in 2005 that brought buy now, pay later—often shortened to BNPL—to Europe before launching in the United States in 2015. It has grown into one of the largest fintech companies in the world, with over 150 million users and more than 500,000 merchant partners. You see Klarna at checkout online and in physical stores.
Klarna gives you a few ways to pay, and the differences matter:
- Pay in 4. This splits your purchase into four equal, interest-free payments due every two weeks. It is the most popular option and usually works for purchases up to $1,000.
- Pay in 30 Days. This gives you a month to pay the full amount with no interest.
- Financing. This spreads larger purchases over 6 to 36 months, with APRs ranging from 0% to 29.99%, depending on your credit.
Pay in 4 and Pay in 30 Days use a soft credit check that does not hurt your score when you sign up. Financing uses a hard credit check, which can lower your score by a few points. Klarna charges late fees of up to $7 per missed Pay in 4 payment. Additionally, since 2022, it reports payment history to the credit bureaus, so your Klarna activity shows up on your credit report.
Read: Do BNPL Installments Count as Debt? Latest 2026 Answer
Is Klarna Legit and Safe to Use
Klarna is legitimate. The company has operated since 2005, is regulated as a bank in Sweden, and partners with major retailers like Walmart, Macy’s, and Nike. It processes billions of transactions a year. As for whether Klarna is a real, trustworthy company, there is no doubt.
Safe is a different word from legit, though. Being a legitimate company does not mean Klarna is automatically safe for your finances. The concern regulators have raised about BNPL is that it makes it easy to pile up debt across several apps without realizing the total. If you stack Klarna with Affirm and Afterpay at the same time, you can end up juggling a dozen payment dates and lose track of what you owe.
Klarna added late fees in some markets after its data showed that charging a small fee helped people pay on time. The logic holds up, but a late fee still stings when you are behind. Reviews reflect this split. Many shoppers love Klarna for interest-free payments on things they were going to buy anyway.
The common complaints are late fees adding up, accounts getting frozen after a missed payment, and the headache of tracking purchases across different stores. So Klarna is legit and safe when used with discipline, but risky when used on impulse.
Klarna Costs and Fees
Pay in 4 is genuinely free when you pay on time. A $400 purchase becomes four payments of $100 with no interest and no added cost. That is what makes Klarna attractive for spreading out a planned purchase.
Costs appear when you slip. Klarna charges up to $7 per missed Pay in 4 payment. That sounds small, but it multiplies quickly. Miss two payments across three different Klarna purchases, and you are looking at $42 in late fees. Fees are capped at 25% of the order value, which protects you on small purchases but not on larger ones.
Financing is where real interest shows up. APRs run from 0% to 29.99%, depending on your credit and the plan. Some offers advertise 0% for 6 or 12 months, but if you do not pay the balance in full before that window closes, you may be charged deferred interest on the original purchase amount. That deferred interest trap catches people who thought the deal was free.
Financing is where real interest shows up. APRs run from 0% to 29.99%, depending on your credit and the plan. Some offers advertise 0% for 6 or 12 months, but if you do not pay the balance in full before that window closes, you may be charged interest on the original purchase amount. That deferred interest trap catches people who thought the deal was free.
Here is how the same $600 purchase can play out:
| Payment method | What do you pay for $600 | Extra cost |
|---|---|---|
| Pay in 4, on time | $600 | $0 |
| Pay in 4, one missed payment | $607 | $7 late fee |
| Pay in 4, two missed payments | $614 | $14 in late fees |
| Financing at 24.99% over 12 months | About $683 | About $83 in interest |
The takeaway is simple. Klarna is cheapest when you treat Pay in 4 as a schedule you will not miss. The moment you slide, or use financing without a payoff plan, the cost climbs.
Read: The Risks of Juggling Multiple BNPL Purchases: What You Must Know Now
How Klarna Affects Your Credit
Klarna started reporting to credit bureaus in 2022, which changed the stakes. Before then, Klarna’s activity only touched your credit report if you used financing or seriously defaulted. Now, Klarna reports payment history to Experian and TransUnion across its payment types.
Here is what that means in practice:
- Pay in 4 uses a soft check at signup, so applying does not hurt your score. But missed payments can be reported, and a single 30-day late payment creates a negative mark that can stay on your report for up to seven years.
- Financing uses a hard check, which can shave a few points off your score. Applying for financing on three purchases in one month causes those hard pulls to stack up, making it look like you are chasing credit.
- Heavy BNPL use can still hurt you, even if you pay on time. When you apply for a mortgage or car loan, active BNPL balances can raise your debt-to-income ratio and make you look less stable than someone who pays cash.
For a real example, imagine you have three Klarna plans running at once and forget one $100 payment for a full month. You pay a $7 late fee, the missed payment gets reported, and your score can drop by 50 points or more if it was previously in good shape. That single slip can raise the interest rate you are offered on a future auto loan, costing far more than the original purchase.
On-time payments can help build a positive record now that Klarna reports them, but the downside risk is significant. Credit damage from Klarna almost always comes from missed payments and stacking too many plans at once.
On-time payments can help build a positive record now that Klarna reports them, but the downside risk is real. Credit damage from Klarna almost always comes from missed payments and from stacking too many plans at once.
5 Tips for Using Klarna Safely
If you are going to use Klarna, a few simple habits will keep it working for you rather than against you. These tips apply to Pay in 4 and financing alike.
- Only use it for planned purchases. Klarna should spread out something you already budgeted for, not talk you into a new buy. If the item was not on your list before you saw the pink button, close the tab.
- Set payment reminders the day you buy. The highest cost with Klarna is the late fee for missed payments. Add each due date to your calendar right away, or turn on autopay from an account with sufficient funds.
- Never run more than one or two Klarna plans at once. Stacking is where people lose track. Two plans with clear due dates are manageable. Six plans across six stores add up to $7, which then totals $40.
- Skip financing unless you have a payoff date locked in. The 0% financing offers only stay free if you pay the balance in full before the promotional period ends. If you cannot commit to that date, deferred interest can wipe out your savings.
- Ask if you could pay cash instead. If you already have the money, paying in full removes every risk: no fees, no tracking, and no credit exposure. Think of it this way: if buying the item on Klarna feels like a relief because you could not pay for it otherwise, that is the clearest signal to wait. Klarna is a timing tool for the money you have, not a way to spend money you do not have.
Read: BNPL and Returns: What Actually Happens to Your Payments
Who Should Use Klarna and Who Should Avoid It
Klarna fits some shoppers well and hurts others. The difference comes down to discipline and cash flow, not income level.
Klarna works for the disciplined budgeter. If you track your spending, never miss due dates, already have the money in your account, and are buying something on your list, Pay in 4 is a clean way to manage cash flow over six weeks. It can also help a careful credit builder with a thin file, since on-time payments now report to the bureaus, provided you are not juggling other BNPL accounts.
Klarna is risky for three types of shoppers. Impulse buyers click “Pay with Klarna” without thinking, justify purchases because the payments feel small, and shop when bored or stressed. Budget stretchers reach for Klarna precisely because they cannot afford full price today—often while already carrying other balances—and one surprise expense can put everything behind.
Finally, forgetful spenders struggle to remember due dates, even with reminders, and find managing multiple schedules overwhelming. If you see yourself in any of these categories, Klarna will likely cost you more than it saves.
Klarna vs Other BNPL Options
Klarna is not the only buy now, pay later service, and its main competitors operate similarly, with only minor differences.
| Service | Payment structure | Late fees | Interest |
|---|---|---|---|
| Klarna | Pay in 4, Pay in 30, financing | Up to $7 per missed payment | 0% to 29.99% on financing |
| Affirm | Pay in 4 and longer loans | No late fees | 0% to 36% on loans |
| Afterpay | Pay in 4 every two weeks | Capped at 25% of the order | Mostly interest-free |
Affirm avoids late fees entirely, which beats Klarna on that point, but its longer loans can carry higher interest rates. Afterpay uses nearly the same four-payment split as Klarna and caps late fees at 25% of the order. All three share the same core risk: easy checkout that quietly encourages overspending.
Better Alternatives to Consider
Depending on your situation, a few options beat BNPL outright:
- A credit card with 0% intro APR. If you have good credit, you can get 12 to 18 months interest-free, earn rewards, and keep fraud protection. The catch is you need discipline to clear it before the promo ends.
- A debit card. You spend only what you have, with no payment schedule, no late fees, and no interest. The “pain of paying” naturally slows down impulse spending.
- Cash and saving up. Old-fashioned but completely debt-free. Waiting until you can afford something removes every tracking and credit risk, and often removes the urge to buy at all.
Read: BNPL vs Store Credit Cards: Which One Should You Actually Use in 2026?
What Beem Is and Where It Fits
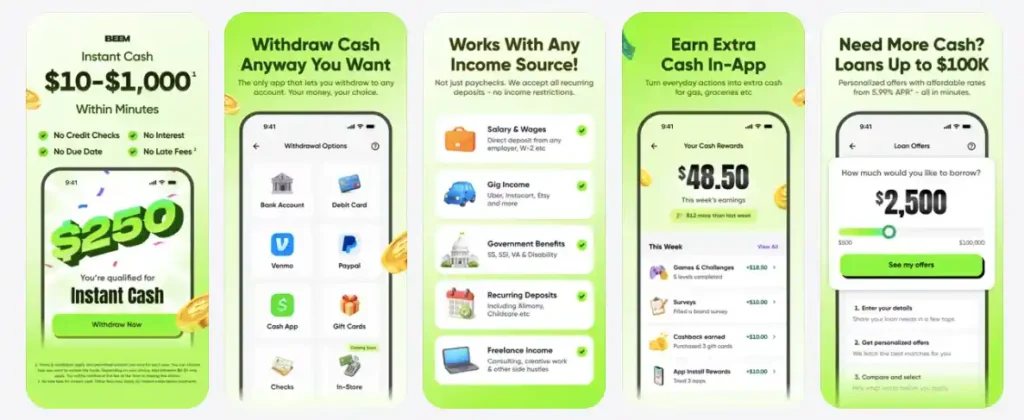
Beem is a money app for people in the United States who need cash help without juggling multiple buy-now, pay-later plans. Where Klarna splits a purchase into installments you track across different stores, Beem gives you cash you can use for the purchase or the bill directly, then repay from your next paycheck.
That difference solves the exact problems Klarna creates. Klarna spreads one purchase into four payments, each with its own due date, plus a $7 fee if you miss one and a credit hit if you miss it by 30 days. Beem’s Everdraft™ feature offers cash access up to $1,000 with no interest. Instead of turning a $600 purchase into four Klarna payments over six weeks, you can access cash, buy the item, and repay it in a single payment on payday.
Beem also helps fix the underlying cash-flow problem. Its subscription monitor finds recurring charges quietly draining your account—the kind of forgotten memberships that cost $30 to $100 a month. Canceling those frees up money, so you may not need a payment plan in the first place. Beem is a financial technology company, not a bank, and Everdraft is not a loan: there is no interest, no credit check, and no fixed due date, with your available amount based on your account activity.
The short version of Klarna versus Beem is this: Klarna shows up at checkout and tempts you to buy more by making each purchase feel smaller. Beem works when you have a real expense and need to bridge the gap until payday without spreading debt across a dozen due dates.
A $500 Beem advance incurs no interest if you repay on time. Conversely, a $500 Klarna purchase costs nothing only if you make all four payments on time, whereas a single missed payment adds a fee and risks your credit.
When Klarna Might Make Sense
Klarna does have a place. It makes sense for a planned purchase where you get guaranteed interest-free Pay in 4 terms, you already budgeted for the item, and you are confident you will make every payment on time over the six weeks. In that narrow case, it is a clean cash-flow tool.
A large purchase with true 0% financing can also work, but only if you set reminders and pay off the balance before the promo period ends. The moment you carry a balance past that date, deferred interest can undo the entire benefit.
Klarna should never be used for impulse buying or for anything you cannot afford to pay in full today. A payment plan does not change what you can afford. It only spreads the cost over time and adds the risk of late fees and credit damage. For most shoppers most of the time, that trade is not worth it.
Final Verdict
So, is Klarna legit? Yes. Klarna is a legitimate, regulated company that has operated since 2005, serves over 150 million users, partners with major retailers, and shows you the terms before you commit. As for whether the company is real and trustworthy, the answer is clearly yes.
The catch is how easy Klarna makes it to overspend. Late fees reach $7 per missed payment, missed payments now hit your credit report, and stacking purchases across stores turns tracking into a chore. The psychological trick of making a big purchase feel small is the real risk, not the company itself.
For a disciplined shopper buying something already on the list with guaranteed 0% terms, Klarna is fine. For everyone else, the safer paths are a debit card, a 0% credit card you can pay off, or simply saving up. And when the real problem is a cash-flow gap before payday rather than a shopping decision, a no-interest cash advance from Beem solves it without the payment juggling that trips up so many Klarna users. Download the app now.
FAQs About Is Klarna Legit
Is Klarna legit and safe to use?
Yes, Klarna is legitimate. It has operated since 2005, is regulated as a bank in Sweden, and partners with major US retailers. It is safe to use if you pay on time, but it charges late fees up to $7 per missed payment and reports payment history to credit bureaus, so missed payments can hurt your score.
Does Klarna always charge 0% interest?
No. Pay in 4 and Pay in 30 Days are interest-free when you pay on time. Klarna’s financing option charges APRs from 0% to 29.99% based on your credit and the plan. Some 0% financing offers charge deferred interest if you do not clear the balance before the promotional period ends.
Will using Klarna hurt my credit score?
It can. Since 2022, Klarna has reported to Experian and TransUnion. Pay in 4 uses a soft check at signup, so applying does not hurt your score, but a missed payment can be reported, and a 30-day late mark can stay on your report for up to seven years. Financing uses a hard check, which can slightly lower your score.
How much are Klarna late fees?
Klarna charges up to $7 per missed Pay in 4 payment, capped at 25% of the order value. The cap protects you on small purchases, but fees add up quickly if you miss payments across several purchases at once, so tracking every due date matters.
Can I use Klarna for multiple purchases at once?
Yes, but it is where most people get into trouble. Each purchase has its own due date, and managing several at once increases the risk of a missed payment. Keeping to one or two active Klarna plans at a time is the safest approach.
Why might someone choose Beem instead of Klarna?
Beem gives you cash access up to $1,000 with no interest and one repayment from your next paycheck, instead of four payments per purchase spread across different stores. No late fees are stacking across merchants, and Beem adds tools like a subscription monitor to close the cash-flow gap that drives people to reach for BNPL.